If you are thinking about borrowing money in Britain, start with what it will cost you every month. A loan calculator UK monthly payments breakdown turns the headline APR and the loan amount into numbers you can budget around — your monthly payment, and the total interest over the life of the loan. This guide gives worked examples in pounds for the loan sizes UK borrowers ask about most, explains the jargon lenders must show you, and helps you pick a term that fits your budget in 2026.
How a Loan Calculator Works Out UK Monthly Payments
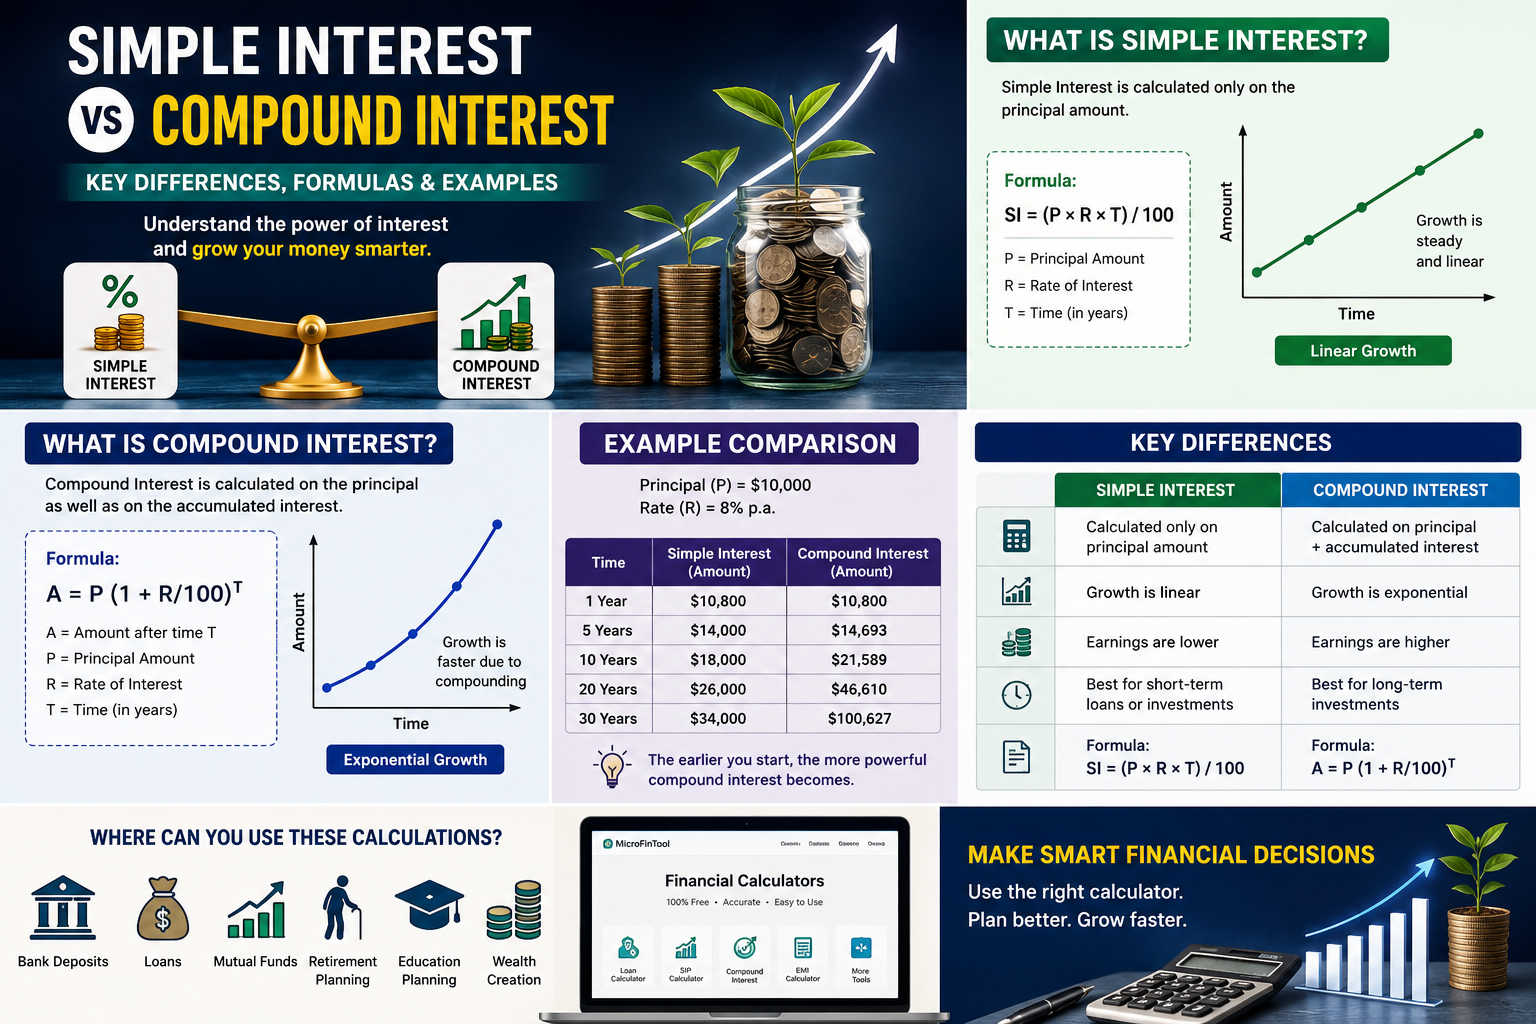
Every personal loan payment in the UK comes down to three ingredients: how much you borrow, the interest rate, and the term. The monthly payment is not simply the loan divided by the number of months, because interest is charged on the remaining balance each month. UK lenders use amortisation: every payment covers that month’s interest first, with the rest chipping away at the balance.
That is why a loan calculator UK monthly payments figure shifts when you move just one dial. Stretch the term and the monthly cost falls — but the total interest climbs, sometimes dramatically. The tables below assume a fixed 8% APR, a fairly typical representative rate for good-credit UK borrowers in 2026. Rates vary by lender and credit score, so treat these as realistic worked examples rather than quotes.
£10,000 Loan: Monthly Payments at 8% Over 1–6 Years
A £10,000 loan sits inside the most competitive band for UK unsecured personal loans. Here is what it costs at a fixed 8% APR:
| Term | Monthly payment | Total repaid | Total interest |
|---|---|---|---|
| 1 year | £869.88 | £10,438.61 | £438.61 |
| 2 years | £452.27 | £10,854.55 | £854.55 |
| 3 years | £313.36 | £11,281.09 | £1,281.09 |
| 4 years | £244.13 | £11,718.20 | £1,718.20 |
| 5 years | £202.76 | £12,165.84 | £2,165.84 |
| 6 years | £175.33 | £12,623.93 | £2,623.93 |
Notice how the one-year term costs under £440 in interest, while six years costs over £2,600 — nearly six times as much — for exactly the same £10,000. Short terms are cheap overall, but £870 a month is a heavy commitment for most households.
£25,000 Loan: Monthly Payments at 8% Over 1–6 Years
For bigger plans — a new car, a home extension, or consolidating debts — £25,000 is one of the most common UK loan sizes:
| Term | Monthly payment | Total repaid | Total interest |
|---|---|---|---|
| 1 year | £2,174.71 | £26,096.53 | £1,096.53 |
| 2 years | £1,130.68 | £27,136.37 | £2,136.37 |
| 3 years | £783.41 | £28,202.73 | £3,202.73 |
| 4 years | £610.32 | £29,295.51 | £4,295.51 |
| 5 years | £506.91 | £30,414.59 | £5,414.59 |
| 6 years | £438.33 | £31,559.83 | £6,559.83 |
The six-year term brings the monthly bill down to £438 — one-fifth of the one-year payment — but you hand over £6,560 in interest. That trade-off between an affordable monthly payment and the total cost is the single most important decision you make when taking out a loan.
Loan Calculator UK Monthly Payments: The 2-Year vs 5-Year Trade-Off
The tables above tell the story, but it is worth spelling out for the comparison borrowers make most often: £25,000 at 8% over two years versus five years.
Over two years you pay £1,131 a month and £2,136 in total interest. Over five years you pay just £507 a month — less than half — but £5,415 in interest, more than two and a half times as much.
Which is right for you? Whichever leaves you with a safety buffer. If £1,131 a month would wipe out your emergency savings, the five-year term is the safer choice even though it costs more overall. Most UK high-street lenders — NatWest, Barclays, HSBC, Lloyds — let you overpay or settle early, and under the Consumer Credit Act you can make extra repayments at any time. A sensible strategy: choose the affordable five-year term, then overpay whenever you can. You keep the lower payment as a safety net while cutting the interest in practice.
What “Representative APR” Means — and Why Your Rate May Differ
UK adverts rarely show the rate you will personally be offered. Under FCA rules, a “representative APR” must be the rate that at least 51% of customers who respond to the advert actually receive. That means almost half of successful applicants pay more — sometimes noticeably more — than the headline figure.
The rate you are quoted depends on your credit history, income, existing debts and the lender’s own risk appetite. Rates vary widely, so always run the numbers on the personalised rate you are actually offered, not the advert.
Before you apply, use the lender’s eligibility checker. These run a soft credit search — which leaves no mark on your credit file — and show your likely rate and chance of approval. Only the formal application triggers a hard search that other lenders can see.
The £7,500–£15,000 Borrowing Sweet Spot
This is the band where UK lenders typically advertise their best representative APRs — above £7,500 you get fixed-rate personal loan pricing, while smaller amounts are often charged higher APRs.
That means borrowing £7,500 can sometimes work out cheaper overall than borrowing £5,000 — worth checking with each lender’s own calculator before you decide. It also pays to look beyond the big names: challenger banks, building societies and credit unions all publish representative APRs, and running a soft-search comparison across a few of them takes minutes. Just remember the golden rule — never borrow more than you need simply because the rate looks better, and never borrow at all if the monthly payment does not fit your budget with room to spare.
Frequently Asked Questions
How do I calculate my UK loan monthly payment?
Use a loan calculator with three inputs: the amount you want to borrow, the APR you have been offered, and the term in months. The calculator amortises the loan — splitting each payment between interest and capital — and shows your fixed monthly payment plus the total interest. For a quick sense check, the tables in this guide show worked examples for £10,000 and £25,000 at 8%.
Does the representative APR guarantee my interest rate?
No. Under FCA rules it is the rate at least 51% of customers receive, so your personal offer can be higher. Your actual rate depends on your credit score, affordability checks and the lender — use an eligibility checker for a soft-search quote before applying.
Is a longer loan term always better for monthly payments?
It always lowers the monthly payment, but raises the total interest — often steeply. As the tables show, £25,000 at 8% costs £1,131 a month over two years but only £507 over five years, while interest jumps from £2,136 to £5,415. Choose the shortest term whose payment still leaves you a comfortable buffer.
Can I overpay or repay my UK loan early?
Yes. Under the Consumer Credit Act, UK borrowers can make extra repayments or settle a loan early at any time. Lenders may charge up to two months’ additional interest as an early settlement fee on fixed-rate loans, but overpaying usually still saves you money overall. Check your lender’s terms before you commit.
Conclusion
A loan is not really defined by its headline rate — it is defined by the monthly payment you commit to and the total interest you end up paying. Run the numbers before you sign anything: try the amount you need at two or three terms, compare the personalised APRs from soft-search eligibility checks, and be honest about what your budget can absorb every month. Do that, and borrowing becomes a tool rather than a trap — a predictable cost in 2026 without thousands extra quietly lost to interest.