
What if saving money felt less like a punishment and more like a game you were winning? That’s the whole idea behind the 52-week savings challenge — a beautifully simple plan where you save a tiny amount in week one and increase it by a little each week until, almost without noticing, you’ve built a serious chunk of savings by New Year’s Eve.
Here’s the headline number: follow the classic version and you’ll end the year with £1,378 in your pocket. In dollars it’s $1,378, in euros €1,378 — the maths works in any currency. And the hardest week asks you for just £52. Sounds doable, right? Let’s break it down.
How the 52-week savings challenge works
The rules couldn’t be simpler. In week 1, you save £1. In week 2, you save £2. Week 3: £3. You keep going, adding one pound each week, until week 52 when you save £52. That’s it. There are no apps required, no subscriptions, no catch.
The total? Weeks 1 through 52 add up to £1,378. (Maths fans: it’s 52 × 53 ÷ 2.) You start so small you barely feel it — a pound is a rounding error — and by the time the amounts get meaningful, the habit is already built and the growing balance is motivating you.
Most people do it with a separate savings account or even a literal jar. The key is keeping challenge money apart from everyday spending money. If it sits in your current account, week 30’s £30 will mysteriously evaporate into takeaways. Open a free instant-access savings pot — most UK banking apps let you create one in about two minutes — label it “52-Week Challenge,” and move the money on the same day each week.
What it feels like, month by month
Months 1–3 (weeks 1–13): Almost suspiciously easy. You’re saving £1 to £13 a week, and your total after three months is just £91. You’ll wonder if this is even worth it. It is — you’re building the habit, and the habit is the whole point.
Months 4–6 (weeks 14–26): Things get real. Weekly amounts climb from £14 to £26, and by the halfway mark you’ve got £351 saved. That’s actual money now — enough for a weekend away or a chunk of Christmas shopping. Motivation usually peaks here because the balance finally looks impressive.
Months 7–9 (weeks 27–39): The grind. £27 to £39 a week starts to pinch, especially in expensive months. This is where most people quit. If you push through, you’ll hit £780 by week 39 — and quitting now would mean abandoning nearly eight hundred pounds of progress.
Months 10–12 (weeks 40–52): The home stretch, and the amounts are spicy: £40 to £52 a week. But here’s the trick — by now you’re a person who saves every week. It’s just what you do. And on week 52, you look at £1,378 and feel like a financial genius. Because honestly? You kind of are.
The reverse version (and why many prefer it)
The classic challenge has one design flaw: the hardest weeks land in December, right when Christmas spending is at its worst. The reverse 52-week savings challenge fixes this elegantly — you start with £52 in week 1 and decrease by £1 each week, finishing with a breezy £1 in the final week of December.
The total is identical: £1,378. But psychologically it’s much easier. You front-load the pain when motivation is highest (fresh January energy!), and the challenge gets easier exactly when life gets more expensive. If you’ve tried the classic version before and stalled around October, try the reverse. It was made for you.
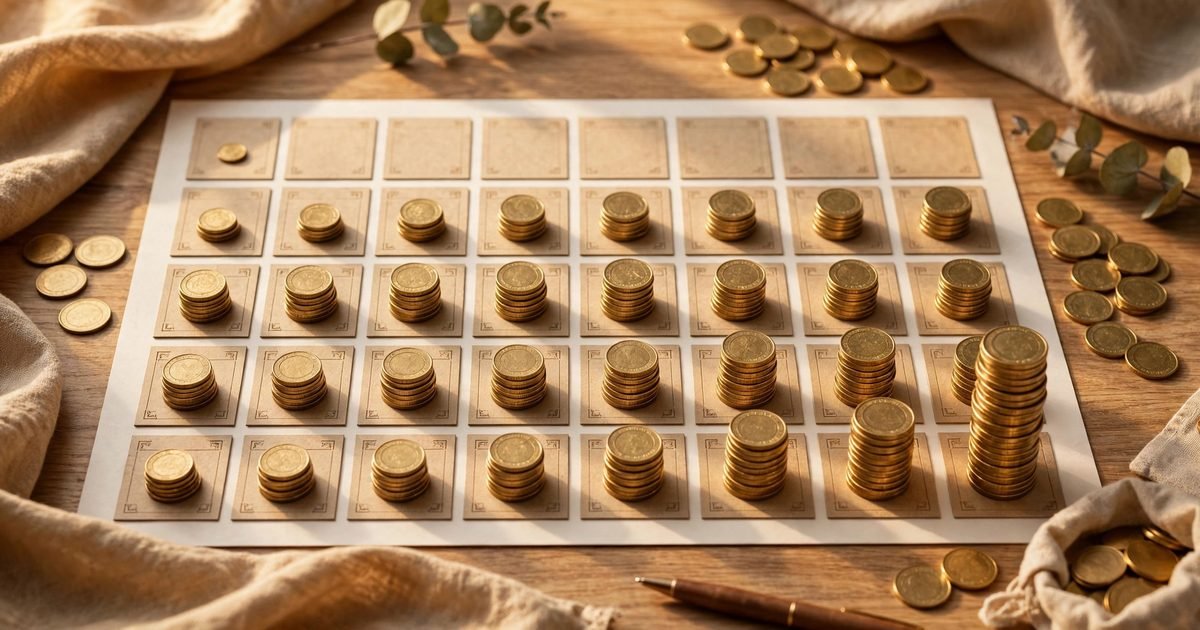
There are other variations too. The biweekly version doubles each deposit (£2, £4, £6…) but you only pay every two weeks — 26 deposits, same £1,378 total, fewer transactions to remember. The pick-a-number version lets you save any remaining week-number amount each week and cross it off a printed chart — great if your income is irregular, because on a tight week you can pick £5 instead of £40 and catch up later.
How to stick with it on a tight budget
Let’s be real: £52 in one week is not pocket change when money’s tight. Here’s how people actually finish this thing without misery.
Automate the transfer. Set a standing order for payday week amounts, or at least a weekly phone reminder. Decisions you have to remake every week are decisions you’ll eventually skip.
Pair it with one cut. Find one recurring expense to trim and redirect it straight into the challenge. Cancelled a £12.99 streaming service you barely watch? That’s weeks 1–13 covered in one move. Switched to a cheaper supermarket brand for a few items? There’s your mid-year weeks.
Use windfalls as catch-up fuel. Birthday money, a cashback payout, selling something on eBay or Vinted — throw unexpected money at the remaining weeks instead of spending it. One £50 sale can knock out a whole painful December week.
Do it with someone. A partner, a friend, a sibling — text each other every Sunday when you’ve made the transfer. Social accountability is absurdly powerful. Some people even run it as a friendly competition: who finishes all 52 weeks first?
Allow “banked” weeks. If you save £30 in a week when only £20 was due, note the £10 surplus and apply it to a future hard week. The chart police won’t arrest you. Flexibility keeps you in the game.
What to do with £1,378 at the end
First: celebrate. Genuinely. You did something most people never do. Then, be intentional. The three best uses for challenge money are: a starter emergency fund (this covers most surprise bills), wiping out a high-interest debt (a £1,378 dent in credit card debt saves you real interest), or seeding next year’s challenge — imagine starting January with last year’s total already working for you in a savings account earning interest.
What you shouldn’t do is let it melt back into your current account with no plan. Money without a job finds a job you didn’t want — usually at the shops. Decide its purpose before week 52 arrives.
Frequently asked questions
How much do you save with the 52-week savings challenge?
£1,378 in total. You save £1 in week 1, £2 in week 2, increasing by £1 each week up to £52 in week 52. The same total applies in dollars or euros.
What if I miss a week?
Don’t quit — just catch up. Add the missed amount to the next week, or spread it across the next few weeks. Missing one week and stopping is how £1,200 of progress dies; missing one week and continuing is a non-event.
Is the reverse 52-week challenge better?
For most people, yes. Starting at £52 and decreasing means the hardest payments happen in January when motivation is high, and December’s payments are tiny when holiday spending peaks.
Can I do the challenge with irregular income?
Absolutely — use the pick-a-number variation. Print a 1–52 chart, and each week save whichever remaining number fits your budget, crossing it off. You’ll still finish with £1,378.
Conclusion
The 52-week savings challenge works because it respects how humans actually behave: start tiny, build the habit, let momentum do the heavy lifting. £1,378 won’t make you rich, but it will make you a saver — and that’s a far bigger prize. Pick your version, set up the transfer, and cross off week one today. Future you, staring at that balance in December, says thanks.