
Table of Contents
- What Is Simple Interest?
- What Is Compound Interest?
- Simple Interest vs Compound Interest: Key Differences
- Simple Interest Formula (With Example)
- Compound Interest Formula (With Example)
- Side-by-Side Comparison Table
- Which One Grows Your Money Faster?
- Real-World Applications
- Common Mistakes to Avoid
- Expert Tips
- FAQs
- Conclusion
Detail’s
Every loan, savings account, and investment product uses one of two interest models: simple or compound. Most people assume they’re roughly the same. They are not — and the gap between them widens dramatically over time.
This guide explains exactly how each works, when each applies, and how to calculate both correctly.
What Is Simple Interest?
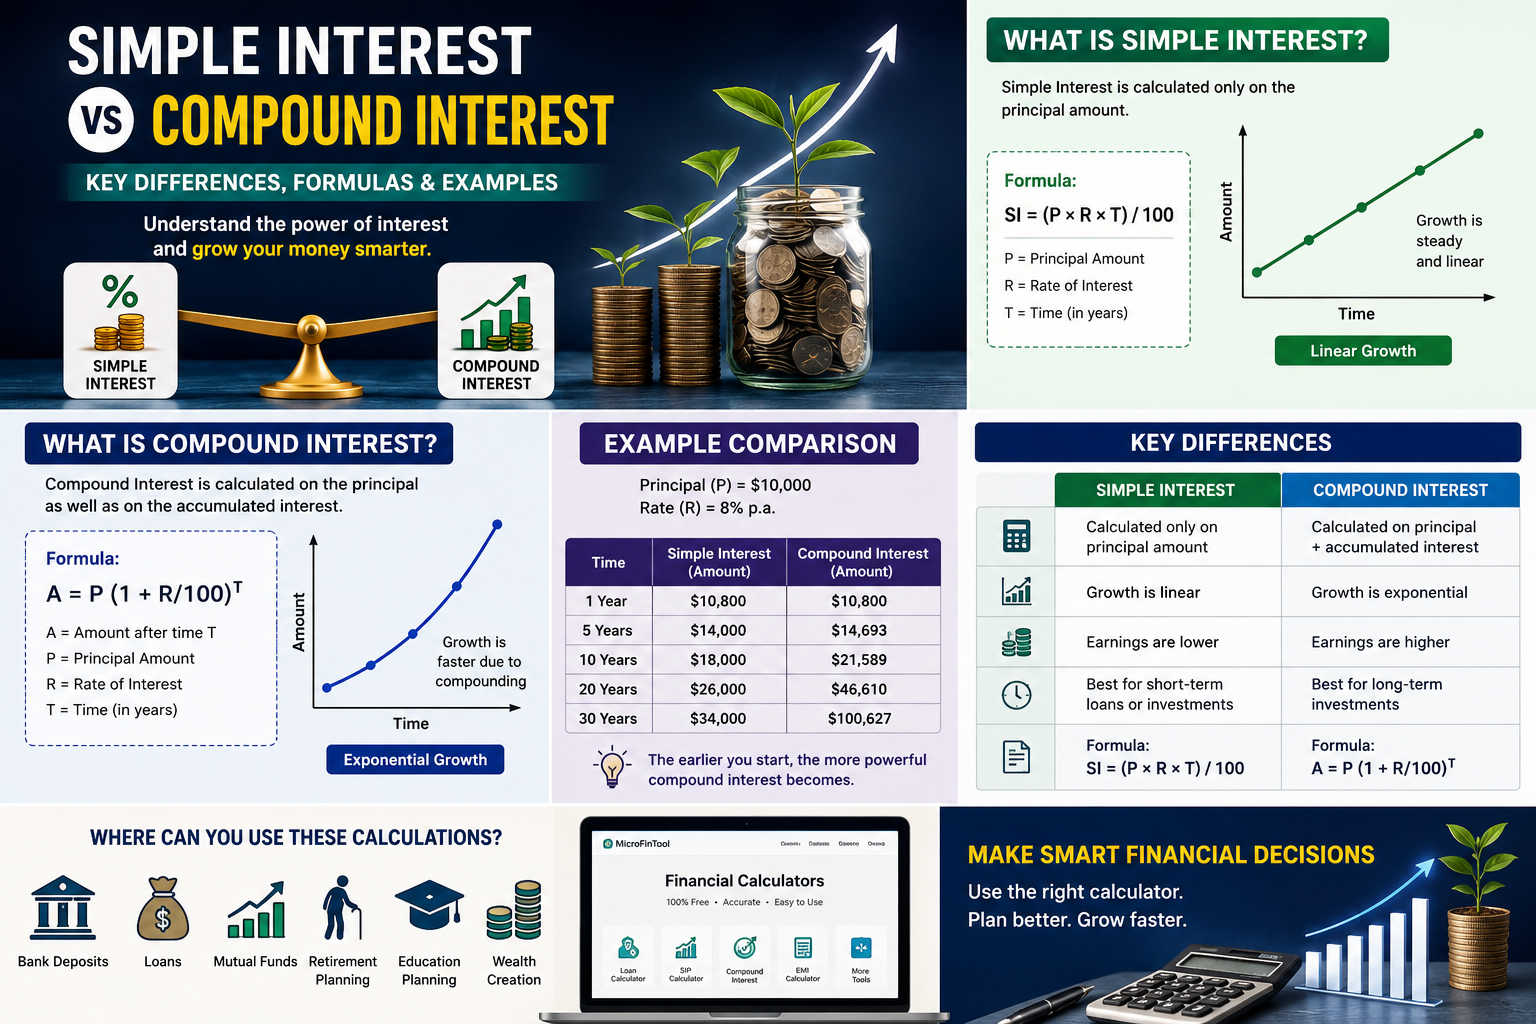
Simple interest is calculated only on the original principal amount, for the entire duration of the loan or investment. The interest earned or owed never changes based on previously accumulated interest.
Where you’ll see it:
- Short-term personal loans
- Car loans (in many countries)
- Some fixed-rate bonds
- Basic savings certificates
Because the interest doesn’t compound, simple interest is easier to predict and calculate — but it also means your money grows more slowly.
What Is Compound Interest?
Compound interest is calculated on the principal plus any interest already earned. Each period, the interest itself starts earning interest — which is why it’s often called “interest on interest.”
Where you’ll see it:
- Savings accounts
- Credit cards
- Mutual funds and retirement accounts
- Most long-term loans and mortgages
The more frequently interest compounds — daily, monthly, quarterly, annually — the faster your balance grows (or your debt grows, if you’re the one paying it).
Important Note: Compound interest works in your favor when you’re saving or investing, but against you when you’re borrowing — especially on credit cards, where interest often compounds daily.
Simple Interest vs Compound Interest: Key Differences
| Factor | Simple Interest | Compound Interest |
|---|---|---|
| Calculated on | Principal only | Principal + accumulated interest |
| Growth pattern | Linear | Exponential |
| Complexity | Easy to calculate | Requires compounding formula |
| Best for borrower | Yes (lower cost) | No (higher cost) |
| Best for saver/investor | No (lower return) | Yes (higher return) |
| Common use cases | Short-term loans, auto loans | Savings, investments, credit cards |
Simple Interest Formula (With Example)
Formula:
SI = (P × R × T) / 100
Where:
- P = Principal amount
- R = Annual interest rate (%)
- T = Time period (in years)
Worked Example
You deposit $5,000 at a 6% annual simple interest rate for 3 years.
SI = (5000 × 6 × 3) / 100 = $900
Total amount after 3 years: $5,000 + $900 = $5,900
Notice the interest earned each year is identical — $300 per year, every year.
Compound Interest Formula (With Example)
Formula:
A = P (1 + R/N)^(N×T)
Where:
- A = Final amount
- P = Principal
- R = Annual interest rate (decimal)
- N = Number of times interest compounds per year
- T = Time in years
Worked Example
Same numbers: $5,000 at 6% for 3 years, compounded annually (N=1).
A = 5000 (1 + 0.06/1)^(1×3)
A = 5000 (1.06)^3
A = 5000 × 1.191016
A = $5,955.08
Compound interest earned: $955.08 — that’s $55.08 more than simple interest, just from a 3-year, $5,000 example. Stretch that to 20 years and the gap becomes massive.
Side-by-Side Comparison Table
| Year | Simple Interest Balance | Compound Interest Balance |
|---|---|---|
| 1 | $5,300 | $5,300.00 |
| 2 | $5,600 | $5,618.00 |
| 3 | $5,900 | $5,955.08 |
| 10 | $8,000 | $8,954.24 |
| 20 | $11,000 | $16,035.68 |
Pro Tip: The longer the time horizon, the more compound interest outperforms simple interest. This is why starting to invest early matters more than investing large amounts later.
Which One Grows Your Money Faster?
Compound interest always outgrows simple interest over any period longer than one compounding cycle — assuming the same principal, rate, and time. This is the mathematical foundation behind the “time value of money” and why financial advisors emphasize starting early.
As a saver or investor: you want compound interest, and you want it compounding as frequently as possible (daily or monthly beats annually).
As a borrower: you want simple interest, since it keeps your total repayment amount lower and predictable.
Real-World Applications
- Auto Loans — Often use simple interest, so paying extra toward principal early reduces total interest paid.
- Credit Cards — Use compound interest, often compounded daily, which is why unpaid balances grow quickly.
- Savings Accounts — Use compound interest; look for accounts that compound daily or monthly for maximum growth.
- Retirement Accounts (401k, mutual funds) — Compound interest is the core mechanism behind long-term wealth building.
- Personal/Microfinance Loans — May use either model depending on the lender; always confirm before signing.
Common Mistakes to Avoid
- Assuming all loans use simple interest — many personal and business loans actually compound.
- Ignoring compounding frequency — a 6% rate compounded daily earns more than 6% compounded annually.
- Not checking the Annual Percentage Yield (APY) on savings products, which reflects true compound growth.
- Paying only the minimum on compound-interest debt — this lets interest compound against you indefinitely.
- Comparing loan offers by interest rate alone without checking whether it’s simple or compound.
Expert Tips
- Always ask lenders directly: “Is this simple or compound interest, and how often does it compound?”
- Use an online calculator rather than manual math when comparing loan or investment offers — small formula errors compound too.
- For debt, prioritize paying off compound-interest balances (like credit cards) before simple-interest loans.
- For savings, prioritize accounts with the highest compounding frequency, not just the highest stated rate.
FAQs
1. What is the main difference between simple interest and compound interest?
Simple interest is calculated only on the original principal, so it grows at a constant rate. Compound interest is calculated on the principal plus previously earned interest, so it grows exponentially. Over time, compound interest produces significantly higher returns or debt than simple interest.
2. Which is better for loans, simple or compound interest?
Simple interest is generally better for borrowers because the total cost stays lower and predictable. Compound interest, especially compounded daily or monthly, can significantly increase the total amount owed over the loan’s lifetime, particularly on revolving debt like credit cards.
3. Which is better for savings, simple or compound interest?
Compound interest is better for savers and investors. Because interest earns interest, your balance grows faster the longer it stays invested. Look for savings accounts or investment products with frequent compounding — daily or monthly outperforms annual compounding.
4. How do I calculate compound interest manually?
Use the formula A = P(1 + R/N)^(N×T), where P is principal, R is the annual rate, N is compounding frequency per year, and T is time in years. Subtract the principal from the final amount (A) to find the total interest earned.
More Importent
5. Does compounding frequency really make a difference?
Yes. A higher compounding frequency means interest is calculated and added more often, so each new calculation includes more accumulated interest. Daily compounding will always yield a higher final balance than annual compounding, given the same nominal interest rate.
6. Can a loan switch between simple and compound interest?
No, the interest type is fixed by the loan agreement and doesn’t change mid-term. However, some loans use different calculation methods for different scenarios, such as early repayment penalties, so always read the full terms before signing.
7. Is credit card interest simple or compound?
Credit card interest is compound, and it’s usually compounded daily. This is why unpaid balances can grow quickly even at moderate stated interest rates — daily compounding accelerates the total amount owed far faster than annual compounding would.
8. What is the Rule of 72 and how does it relate to compound interest?
The Rule of 72 estimates how many years it takes an investment to double under compound interest: divide 72 by the annual interest rate. For example, at 6% interest, money doubles in approximately 12 years (72 ÷ 6 = 12).
Conclusion
The choice between simple interest vs compound interest isn’t just academic — it directly affects how much you’ll pay on a loan or earn on your savings. Simple interest stays flat and predictable; compound interest snowballs, working powerfully in your favor when saving and against you when borrowing.
Rather than doing this math by hand every time you compare a loan or savings offer, use the free Simple Interest and Compound Interest Calculators on MicroFinTool to instantly see your exact numbers, compare scenarios, and make a confident financial decision.
credit union microloan, digital microfinance, mobile microfinance, mobile money lending, fintech lending platform, online microloan, app based microloan, digital lending platform, e-lending, mobile banking loan, digital credit scoring, alternative credit score, AI credit scoring, blockchain microfinance, microfinance software, loan management software
3 thoughts on “Simple Interest vs Compound Interest: Which One Actually Grows Your Money?”