Here’s a statistic that should make everyone pay attention: women repay microloans at higher rates than men, yet they still receive a smaller share of formal credit worldwide. Microfinance for women isn’t charity — it’s one of the most effective economic engines ever discovered, turning tiny loans into thriving businesses, school fees paid, and entire families lifted out of poverty.
From the Grameen Bank’s pioneering village groups in Bangladesh to mobile-money lending across Africa, microfinance for women has a forty-year track record of results. This guide explains how it works, why it matters so much, and how women entrepreneurs can access it today.
Why Microfinance Targets Women
This isn’t about favoritism — it’s about impact. Study after study shows that when women control household income, more of it goes to children’s nutrition, education, and health than when men control it. A loan to a mother doesn’t just fund a business; it funds a family’s future.
There’s also a practical reason. Women in many developing economies are excluded from traditional banking: no collateral, no formal employment records, no credit history. Microfinance was designed precisely for this gap — small, collateral-free loans based on trust, group guarantees, and character rather than paperwork.
How Microfinance for Women Actually Works
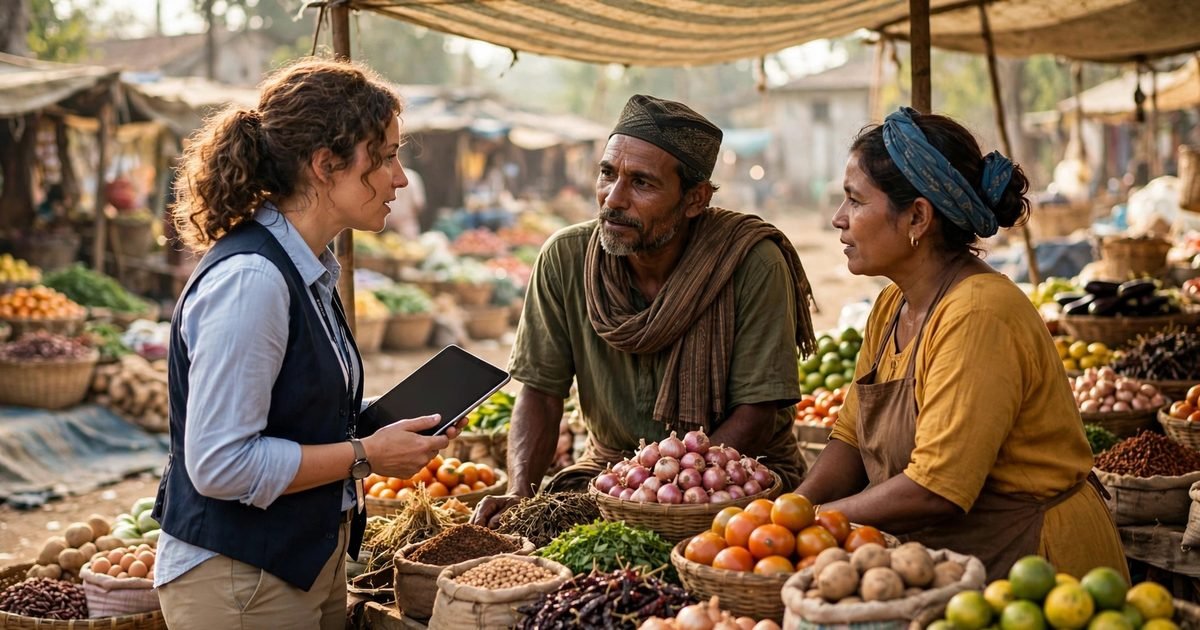
The classic model is beautifully simple. A microfinance institution (MFI) forms a small group of women — often 5 to 20 — who guarantee each other’s loans. Each member receives a small amount, say $50 to $500, to start or expand a tiny business: tailoring, food stalls, goat rearing, mobile phone accessories.
Repayments happen weekly or monthly in group meetings. The social pressure of the group keeps repayment rates extraordinarily high — Grameen-style programs routinely report repayment above 95%. Over time, successful borrowers graduate to larger loans, and many eventually become eligible for formal bank credit. It’s a ladder, and the first rung is deliberately low.
Real Stories: What These Loans Create
Consider Amina, a vegetable seller in rural Pakistan. Her first loan was $100 — enough to buy produce in bulk instead of daily, cutting her costs by a third. Within two years she had a permanent stall, and her daughter became the first in the family to attend secondary school.
Or take the women’s savings groups across Kenya, where members pool small weekly contributions and take turns borrowing from the pot. One group’s treasurer told researchers their members’ average household income doubled within three years — not from one big break, but from dozens of small, well-timed loans.
These aren’t exceptional cases. They’re the normal outcome when determined women get access to fair, small-scale credit.
Top Microfinance Programs Serving Women in 2026
Options vary by region, but several models dominate:
- Grameen-style MFIs — group lending with weekly meetings; widespread across South Asia and expanding in Africa and Latin America.
- Women’s World Banking network — partners with financial institutions to design products specifically for women’s needs, from savings to insurance.
- Kiva — crowdfunded 0%-interest loans where individual lenders worldwide fund women entrepreneurs directly.
- Akhuwat (Pakistan) — interest-free microloans rooted in community trust, with a strong focus on women borrowers.
- Mobile money lenders — digital microloans disbursed via phones (like M-Pesa ecosystems), increasingly popular with women who can’t easily visit bank branches.
Challenges Women Borrowers Still Face
Let’s be honest: the picture isn’t all rosy. Many women borrowers juggle loan repayments with unpaid care work, face restrictions on mobility that make group meetings hard to attend, and sometimes see loans controlled by male relatives despite being in the woman’s name.
Over-indebtedness is another real risk. When multiple lenders chase the same borrowers without checking existing debts, women can end up trapped. Responsible MFIs now check borrower debt levels before lending — and borrowers should be wary of any lender that doesn’t ask about existing loans.
How to Apply: A Practical Checklist
If you’re a woman entrepreneur considering a microloan, here’s how to start:
- Identify legitimate MFIs near you — check your country’s microfinance regulator or ask at women’s community organizations.
- Verify the lender — real MFIs have offices, licenses, and transparent terms (and watch for the loan scam red flags we covered in a recent guide).
- Start small — borrow only what your business plan needs; you can scale up after a successful first cycle.
- Ask about training — the best programs bundle loans with business skills training, which dramatically improves success rates.
- Confirm credit reporting — if the MFI reports to a credit bureau, your repayments build a credit history for bigger opportunities later.
FAQ
Do women really get better microloan terms than men?
Not better terms — but many programs specifically target women because data shows higher repayment rates and greater household impact. Some programs are women-only; most simply prioritize women’s applications.
Can I get a microloan without any collateral?
Yes. That’s the core innovation of microfinance. Group guarantees, character references, and cash-flow assessment replace traditional collateral in most MFI lending.
What business ideas work best for first-time women borrowers?
Low-startup-cost, cash-flow-positive ideas: food preparation and selling, tailoring, beauty services, small retail, poultry or goat rearing, and mobile money agency work. Pick something matching skills you already have.
Are interest-free microloans real?
Yes — organizations like Akhuwat in Pakistan offer genuinely interest-free (qard-hasan) microloans funded by donations and recovered capital. Availability depends on your region.
Conclusion
Microfinance for women works because it bets on the world’s most reliable borrowers and most impactful spenders. A $200 loan in the right hands doesn’t just start a business — it keeps kids in school, improves family nutrition, and builds a credit history that opens bigger doors. If you’re a woman entrepreneur with a plan but no capital, that first small loan might be closer than you think. Find a legitimate MFI, start small, repay faithfully — and watch what happens next.