
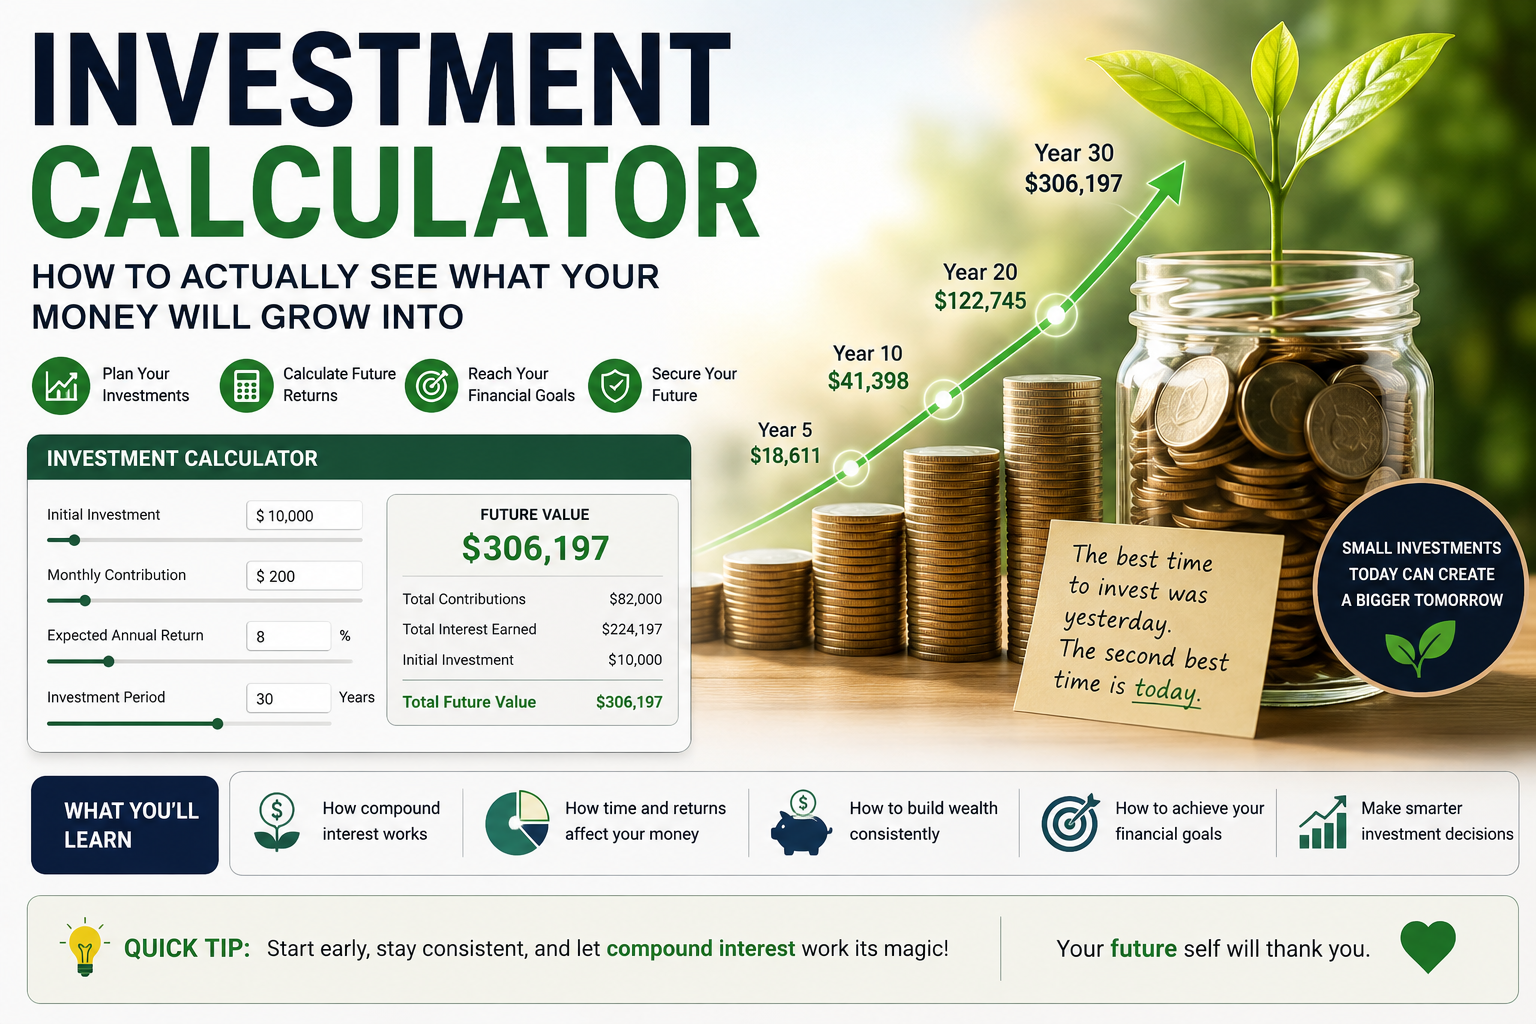
Most people think about investing in vague terms — “I’ll put some money away and it’ll grow.” An investment calculator replaces that vagueness with an actual number: exactly what your money could ecome in 10, 20, or 30 years, based on how much you invest, how often, and at what rate of return. This
guide walks through how to use one properly, what inputs actually matter, and the mistakes that leadpeople to either overestimate their future wealth or underinvest out of unnecessary caution.
Investment Growth Calculator
Dekhein ke aapki investment compound growth se waqt ke sath kitni barhegi.
What an Investment Calculator Actually Shows You
At its core, an investment calculator takes your starting amount, your ongoing contributions, your expected rate of return, and your time horizon, and projects forward what your investment could be worth. But a well-built calculator does more than spit out a single final number. It shows you:
- How much of your final balance came from your own contributions versus investment growth
- How the growth curve accelerates over time as compounding takes hold
- The difference a few extra years, or a slightly higher contribution, makes to your final total
- How different rate-of-return assumptions change your outcome
This last point matters more than people realize. A calculator isn’t predicting the future — it’s modeling scenarios. The real value is in comparing those scenarios against each other, not treating any single projected number as a guarantee.
The Core Inputs You Need Before You Start
Before you run any numbers, gather these four pieces of information. Each one changes the outcome significantly, so it’s worth being realistic rather than optimistic with your inputs.
1. Starting Amount This is whatever you’re beginning with today — savings you already have set aside for investing. If you’re starting from zero, that’s fine too; the calculator will simply show growth building entirely from your contributions.
2. Contribution Amount and Frequency Are you adding money monthly, quarterly, or annually? Consistency matters more than the exact amount in most cases. A calculator lets you test whether a smaller, automatic monthly contribution outperforms a larger, irregular one — and it usually does, because consistent contributions benefit more fully from compounding over time.
3. Expected Rate of Return This is the input people most often get wrong, usually by being too optimistic. Historical stock market averages are often cited around 7-10% annually before inflation, but that figure varies significantly by asset mix, time period, and market conditions. It’s worth running your numbers at a conservative rate, a moderate rate, and an optimistic rate, rather than anchoring to just one.
4. Time Horizon How many years until you need this money? This is the single biggest lever in most investment calculations. A longer time horizon doesn’t just mean more contributions — it means more compounding cycles, which is where the bulk of long-term growth actually comes from.
How to Read Your Results the Right Way
Once you’ve entered your numbers, resist the urge to just look at the final total and feel good or bad about it. Here’s what actually matters in the output:
- Contributions versus growth — In many long-term projections, the amount you contributed ends up being a smaller portion of the final total than the growth generated by compounding. Seeing this breakdown is often the most motivating part of running the numbers.
- The compounding curve — Growth in the early years looks slow and unremarkable. It’s in the later years that the curve visibly steepens. This is normal, not a sign that something is wrong with your plan — it’s simply how compound growth behaves.
- Sensitivity to rate assumptions — Run the same inputs at a lower and higher rate of return. The gap between those two outcomes tells you how much uncertainty is baked into any long-term projection, which is useful context for setting realistic expectations.
Common Mistakes People Make With Investment Calculators
Using an unrealistically high rate of return. It’s tempting to plug in the best historical year you’ve heard about and let the calculator show an inflated result. A more useful approach is to run multiple scenarios and plan around the conservative end.
Ignoring inflation entirely. A number that looks impressive today may buy considerably less in 20 or 30 years. Some calculators let you enter an inflation-adjusted return; if yours doesn’t, it’s worth mentally discounting the final figure.
Treating the projection as a guarantee. An investment calculator models a scenario based on assumptions you provide — it doesn’t predict actual market performance. Markets don’t grow in a smooth straight line, even if the calculator’s output looks that way.
Underestimating the value of starting early. People often delay investing until they have a large enough amount to feel like it’s “worth it.” Running the numbers on starting now with a modest amount versus waiting five years with a larger amount usually makes a compelling case for starting immediately.
Forgetting to account for fees. Investment fees, even small annual percentages, compound the same way returns do — except against you. A calculator that doesn’t let you factor in fees will overstate your realistic outcome.

A Simple Step-by-Step Way to Use One
- Enter your current starting amount, even if it’s zero.
- Set a realistic, sustainable contribution amount and frequency.
- Run the calculation at three different rate-of-return assumptions: conservative, moderate, and optimistic.
- Test your actual time horizon, then test it again with five extra years added.
- Compare the contributions-versus-growth breakdown across each scenario.
- If available, factor in estimated fees and inflation for a more realistic final number.
- Use the comparison, not any single number, to inform your actual investment decisions.
Final Thoughts
An investment calculator is at its most useful not as a crystal ball, but as a tool for comparison — showing you how time horizon, contribution consistency, and rate assumptions interact to shape a long-term outcome. The specific final number matters less than understanding the relationships behind it: that starting earlier beats waiting for a bigger lump sum, that consistent contributions compound more effectively than sporadic ones, and that even modest, realistic assumptions can produce meaningful growth given enough time. Run a few different scenarios before drawing conclusions about your own plan, and treat every output as a projection to learn from, not a promise to bank on.
Enter your initial amount, monthly contribution, expected annual return, and time horizon. The calculator projects how your money could grow with compound interest.
Compound interest is when your returns earn returns. Your gains are reinvested, so your balance grows faster over time. Starting early matters more than starting big.
Be conservative. Use 6–8% for long-term stock market estimates, lower for bonds or savings. The calculator shows projections, not guarantees — actual returns will vary.
2 thoughts on “Investment Calculator: How to Actually See What Your Money Will Grow Into”