What if the small loan you take to grow your business could also grow your credit score? For millions of people with thin or nonexistent credit files, that is exactly what happens. Learning how to build credit with microloan repayments is one of the smartest financial moves a first-time borrower can make — because a good credit history opens doors to bigger loans, better rates, and even rental approvals later.
But here is the catch most people miss: not every microloan builds credit. It only works when your lender reports your payments to a credit bureau. So before you sign anything, you need to understand the mechanics. Let’s break down exactly how to build credit with microloan borrowing, step by step.
Why Microloans Are a Great Credit-Building Tool
Traditional wisdom says you need a credit card to build credit. But credit cards require — wait for it — existing credit to qualify. See the problem? Microloans break this cycle because many microfinance institutions lend to people with no credit history at all.
Microloans are also small and short-term, which makes them manageable. Borrowing $500 and repaying it over six months is far less risky than maxing out a $5,000 credit card. Every on-time payment becomes a positive mark on your record, and those marks compound over time.
Step 1: Choose a Lender That Reports to Credit Bureaus
This is the make-or-break step. If your lender doesn’t report to at least one major credit bureau, your perfect repayment record exists only in their filing cabinet. When you want to build credit with microloan payments, always ask upfront: “Do you report borrower repayment data to credit bureaus? Which ones?”
Larger microfinance institutions and digital lenders usually report. Small informal lending groups often don’t. Neither option is bad — but only the reporting lender helps your score. Get the answer in writing before you commit.
Step 2: Borrow Only What You Can Comfortably Repay
Here’s a mistake I see constantly: someone borrows the maximum amount offered instead of what they actually need. Bigger loan, bigger monthly payment, bigger risk of missing one.
For credit-building purposes, smaller is better. A $300 loan you repay flawlessly beats a $2,000 loan you struggle with. Lenders and scoring models reward consistency, not size. Borrow what your budget can handle with room to spare.
Step 3: Never Miss a Payment — Set Up Autopay
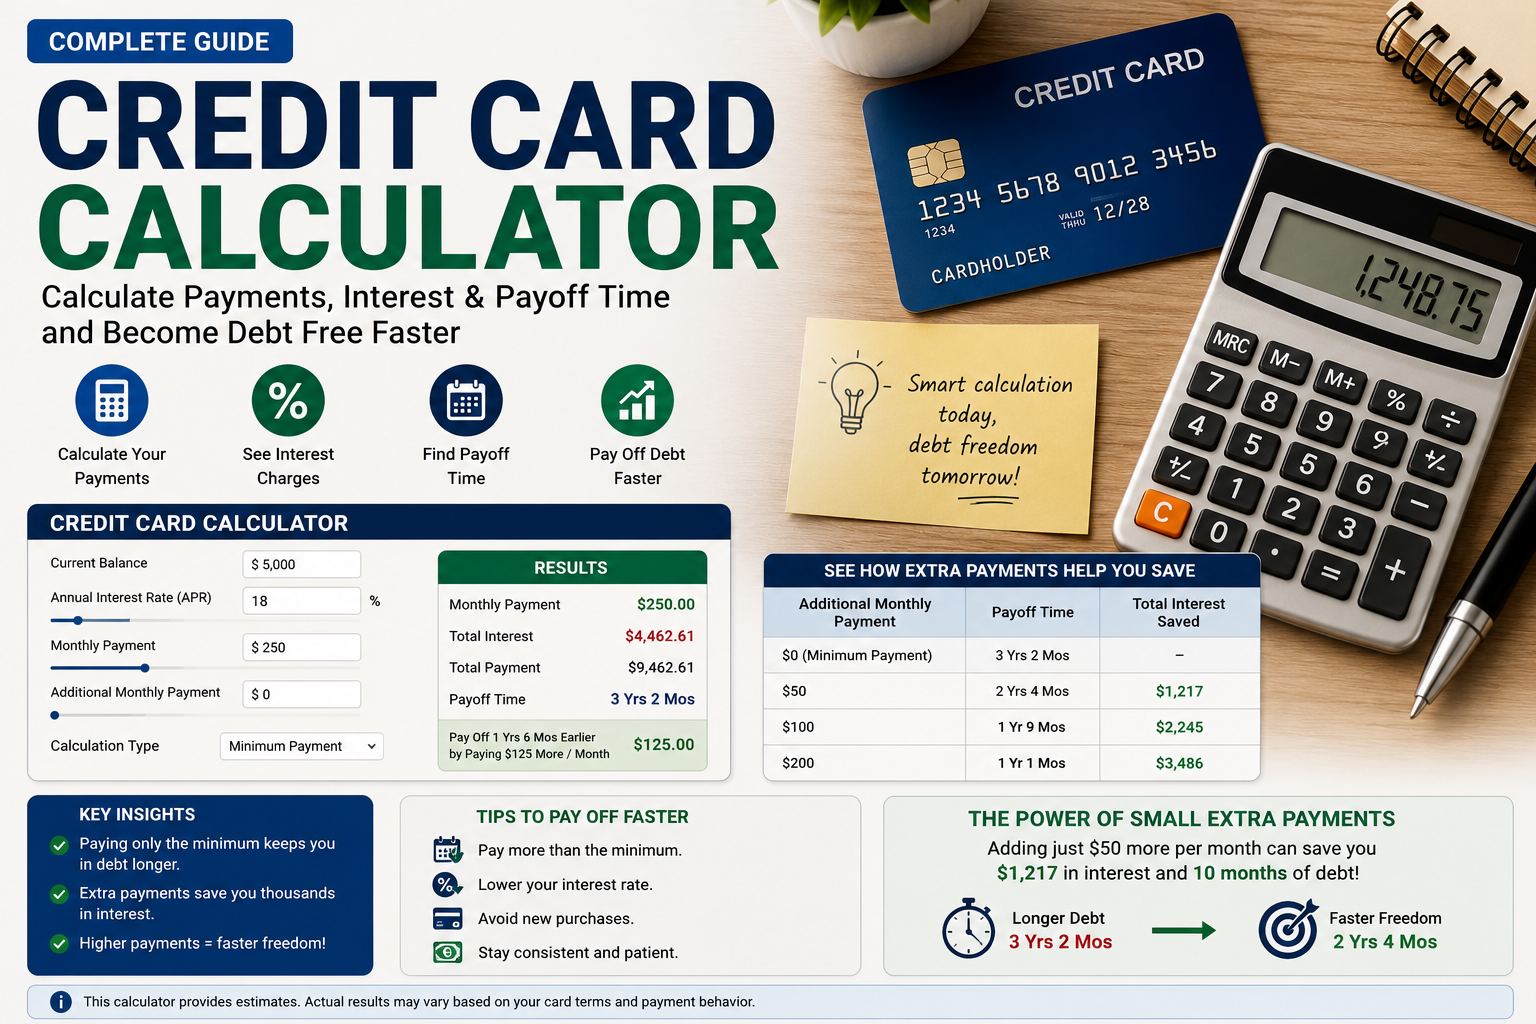
Payment history is the single biggest factor in most credit scores, often worth 35% of the total. One missed payment can undo months of good work, while a streak of on-time payments is pure gold.
The fix is boring but effective: automate. Set up automatic payments from your bank or mobile money account for at least the minimum due, a few days before the deadline. Then treat that money as already spent. If autopay isn’t available, set two reminders — one a week before, one the day before.
Step 4: Keep Your Credit Utilization Low (Yes, It Applies to Loans Too)
Utilization usually refers to credit cards, but the principle applies to microloans as well: owing less relative to your total available credit looks better. If you take a second microloan while the first is still active, your total debt load rises and your score may dip temporarily.
A cleaner strategy? Finish one microloan completely, let the positive history land on your report, then consider the next one. Sequential borrowing builds a longer track record than juggling multiple loans at once.
Step 5: Check Your Credit Report and Dispute Errors
After three to six months of on-time payments, check your credit report. Many countries offer one free report per year from each bureau. Look for your microloan account: is it listed? Are the payments marked on time? Is the balance correct?
Errors are shockingly common — wrong dates, missing accounts, payments marked late that weren’t. If you spot one, dispute it with the bureau in writing. A single corrected error can lift your score noticeably.
How Long Does It Take to See Results?
Be honest with yourself here: credit-building is a slow game. Most borrowers see their first score appear within 3–6 months of consistent reporting, and meaningful improvement typically takes 6–12 months. Anyone promising an overnight 200-point jump is selling you something — possibly a scam (see our guide on loan scam red flags).
The good news? The habits you build — paying on time, borrowing within your means, monitoring your report — pay dividends for decades, long after the microloan itself is forgotten.
FAQ
Will a microloan hurt my credit score at first?
Possibly, slightly. A new account and a hard inquiry can cause a small temporary dip. But consistent on-time payments quickly outweigh that, and most borrowers end up higher than where they started within a few months.
Can I build credit with a microloan if I have no bank account?
Yes, if your lender reports to a bureau that tracks alternative data. Some bureaus now include mobile money repayment histories. Ask your lender which bureau they report to and whether mobile money payments count.
Is it better to repay a microloan early for my credit score?
Not necessarily. Early repayment saves interest, which is great — but a longer history of on-time payments (say, 12 months vs. 3) builds a stronger record. If early repayment has no penalty, weigh the interest savings against the value of a longer positive history.
How long does a microloan take to build credit?
Credit-building is a slow game; most borrowers see their first score movement after several months of consistent on-time payments.
What size microloan builds credit best?
A small, affordable loan you can repay comfortably; on-time payment history matters far more than loan size. For credit-building purposes, smaller is better.
What if my lender doesn’t report to any bureau?
Then the loan won’t directly build your score — but the discipline still matters. Finish it cleanly, then take your next loan from a reporting lender and mention your perfect history with the previous one. Some lenders consider it during manual underwriting.
Conclusion
Knowing how to build credit with microloan repayments turns a simple small loan into a long-term asset. Choose a reporting lender, borrow modestly, automate your payments, and monitor your report. Do that consistently, and the same $500 loan that stocked your shop shelf today could be the reason a bank approves your business loan tomorrow. Start small, stay consistent, and let every payment work twice as hard for you.
Credit-building is a slow game; most borrowers see their first score movement after several months of consistent on-time payments.
A small, affordable loan you can repay comfortably; on-time payment history matters far more than loan size. For credit-building purposes, smaller is better.