Help to Save Scheme Explained: A 50% Bonus on Your Savings
With the help to save scheme explained simply: if you’re on Universal Credit or Working Tax Credit, the government adds 50p for every £1 you save, up to a £1,200 bonus over four years. You save between £1 and £50 a month, and the bonuses are calculated on your highest balance — not what you end with.
It’s the most generous savings deal in the UK, full stop. No bank account pays 50%. Yet take-up has always lagged eligibility, largely because people who’ve never managed to save assume it’s “not for them”. It is — the scheme was literally designed for first-time savers on low incomes.
Who Can Open a Help to Save Account?
You qualify if you’re receiving Universal Credit — and in your last assessment period your household earned at least £1 in take-home pay — or you receive Working Tax Credit. You must live in the UK. One detail couples trip over: each partner can open their own account, so a couple where both qualify can earn two bonuses — up to £2,400 between them.
Good news on the horizon: the scheme has been made permanent, and eligibility is set to widen further from 2028, bringing in an estimated 1.5 million more households. If you’re not eligible today, it’s worth checking again when the expansion lands.
How the Bonus Actually Works
- Months 1–24: save anything from £1 to £50 a month — there’s no penalty for skipping a month.
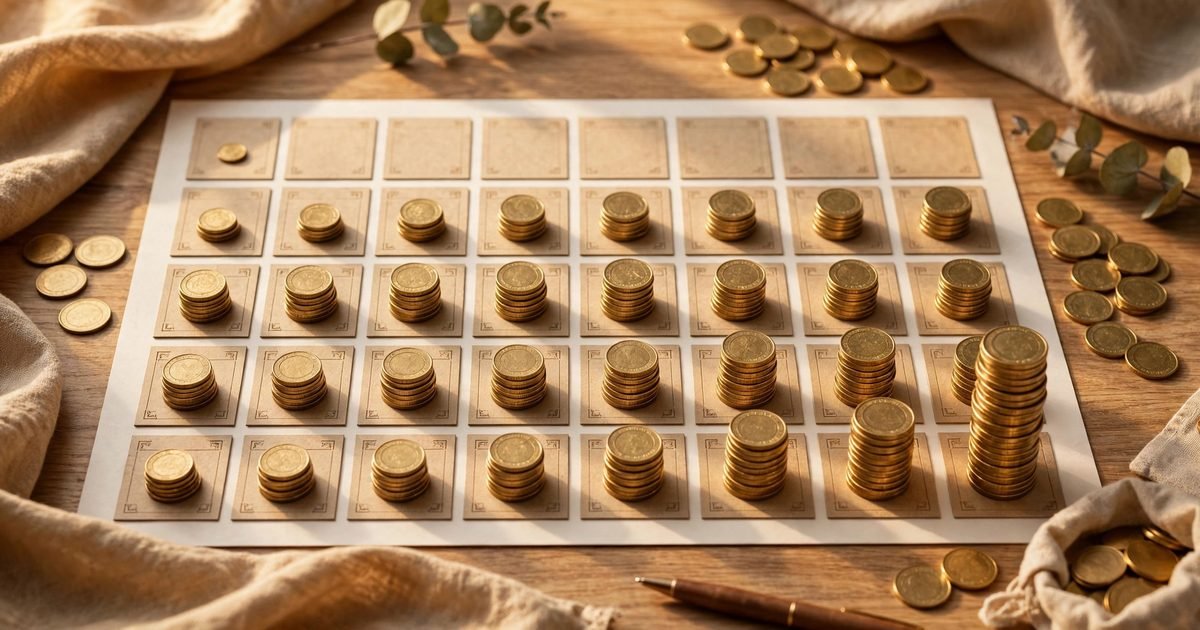
- First bonus (month 24): 50% of the highest balance you reached in the first two years. Hit £1,200 at any point and the bonus is £600.
- Months 25–48: keep saving if you can. The second bonus is 50% of the growth in your highest balance beyond the first period’s peak.
- Maximum total: £1,200 in bonuses on £2,400 saved.
That “highest balance” rule is the scheme’s secret weapon. Need to dip into the account for a broken boiler in month 10? Your bonus is still based on the peak you reached, not the reduced balance afterwards. Most savers put in the full £50 a month — set up a standing order just after payday and you’ll barely notice it leaving.
Opening an Account in Five Minutes
Apply through GOV.UK or the HMRC app using your Government Gateway ID. Approval is usually instant, and you can pay in by debit card, standing order or bank transfer. The account stays open for exactly four years from the month you open it, then closes automatically with your final bonus paid into your nominated bank account.
Will Saving Affect Your Benefits?
This is the worry that stops people applying, so let’s be clear. Money in Help to Save, plus the bonuses, does not count towards the £16,000 savings limit for Universal Credit while the account is open — it is disregarded capital. Your own savings outside the scheme follow the normal rules: savings between £6,000 and £16,000 reduce UC gradually, and £16,000 or more stops it. Since most Help to Save savers keep under £2,400 in the account, the practical risk is minimal — but if you hold other savings too, add everything up before you commit.
Help to Save vs a Normal Savings Account
A top easy-access account pays around 4–5% interest. Help to Save pays an effective 50% bonus — ten times more — on money you’re allowed to withdraw whenever you need it. There’s no contest for the first £50 a month you can spare. Only once you’re saving beyond the £50 cap does a regular account (or a Cash ISA) enter the conversation. If you don’t qualify for Help to Save, a Lifetime ISA offers a 25% bonus for first-home or retirement saving, though with stricter withdrawal rules.
The Bottom Line
If you’re on Universal Credit or Working Tax Credit, opening Help to Save is the single best money move available to you: save £50 a month, let the government’s 50% bonuses stack to £1,200, and keep full access to your cash throughout. Five minutes to open, four years, done.
FAQs
Help to save scheme explained: how much bonus can I get in total?
The help to save scheme pays a maximum bonus of £1,200 over four years: up to £600 after year two and up to £600 more after year four. The bonus equals 50% of the highest balance you reach, so saving the full £50 every month for four years earns the maximum.
Can I withdraw money from Help to Save without losing the bonus?
Yes, you can withdraw from Help to Save at any time without penalties or losing bonuses already calculated. Because each bonus is based on the highest balance reached during that period, withdrawals made after you’ve hit a peak do not shrink your bonus — one reason the scheme suits irregular incomes.
What happens to Help to Save if I stop claiming Universal Credit?
If you stop claiming Universal Credit or Working Tax Credit, your Help to Save account stays open for its full four-year term and you can keep saving and earning bonuses. Eligibility is only tested when you apply; later changes to your benefits or income do not close the account.
Can both partners in a couple have Help to Save?
Yes, both partners can each open their own Help to Save account if each individually meets the eligibility rules. That doubles the household’s potential bonus to £2,400 over four years, provided the couple can save up to £50 per month into each account — £100 a month in total.
When does the Help to Save account close?
A Help to Save account closes automatically four years after the month it was opened. At closure, your final bonus is paid into your nominated bank account and your remaining savings are returned; you cannot open a second account afterwards, even if your circumstances change later.