For most beginners, index funds beat individual stocks — and honestly, it isn’t close. A single low-cost index fund buys you a slice of hundreds of companies for fees as low as 0.03% a year, while stock picking demands hours of research every week and most pickers still trail the market over time. If you’re weighing up index funds vs individual stocks for the first time, this guide settles it with numbers, not slogans.
That sounds like a bold claim. It’s also the conclusion of decades of data. Let’s walk through why — and the one situation where buying individual stocks genuinely makes sense.
Index Funds vs Individual Stocks: What You’re Actually Choosing
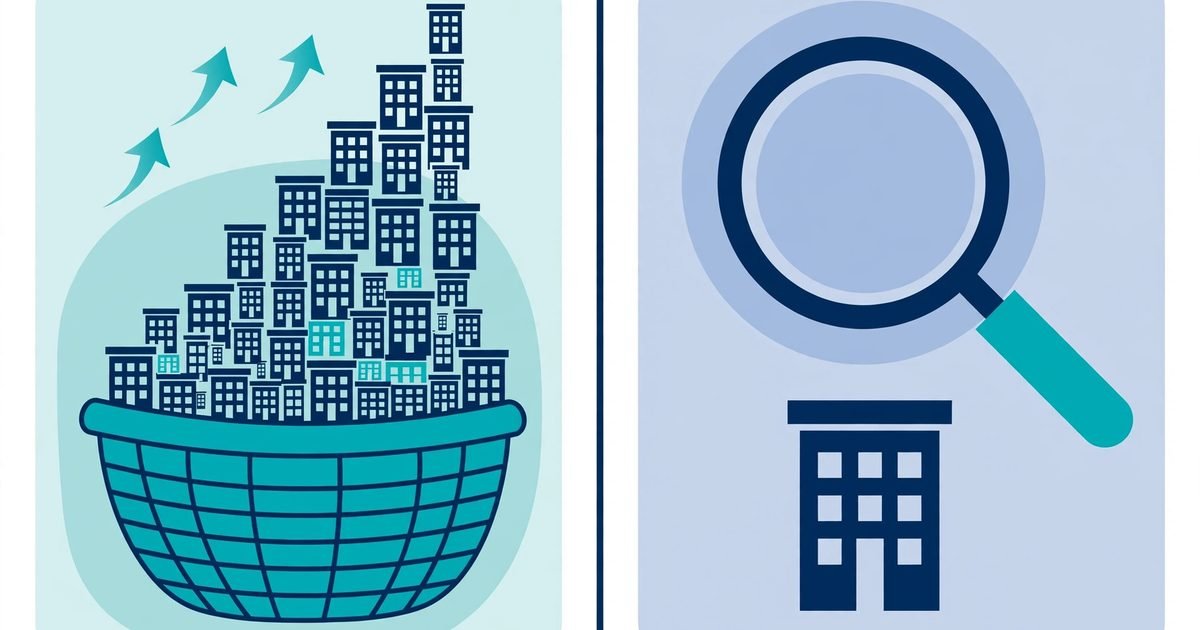
An index fund is a basket that copies a market index. Buy one fund and you instantly own a little of every company in the FTSE 100 or the S&P 500 — hundreds of businesses, one purchase. Individual stocks are the opposite: you research a company, buy its shares directly, and your money rises and falls with that one business.
Vanguard founder John Bogle put it perfectly: “Don’t look for the needle in the haystack. Just buy the haystack.” The haystack, in 2026, costs almost nothing to own. UK-listed trackers like the SPDR S&P 500 charge as little as 0.03% a year; the Vanguard S&P 500 UCITS ETF charges 0.07%. That is the price of owning the entire US market. Try building that yourself, one share at a time.
The Effort Gap Nobody Warns Beginners About
Here’s the comparison that never makes it into the brochure:
- Index funds: pick one global tracker inside your Stocks & Shares ISA, set up a monthly direct debit, check it once a year. Total effort: about an hour a year.
- Individual stocks: read annual reports, follow earnings calls, watch sector news, react fast when something breaks. Realistic effort: five to ten hours a week. That’s a part-time job.
Ask yourself honestly: do you have a spare evening every week to study balance sheets? Most beginners don’t — and here’s the uncomfortable part. Around 90% of professional fund managers, whose literal job is picking stocks, fail to beat their index over a decade. If the pros can’t reliably win with teams of analysts, what exactly is your edge?
There is one honest counter-argument: some people genuinely enjoy the research. If analysing companies sounds like fun rather than homework, that matters. Just don’t confuse “fun” with “profitable”. They’re different hobbies.
The Fee Drag That Quietly Eats Your Returns
Fees sound boring. They compound like everything else — against you.
Take £10,000 invested for 30 years at 8% annual growth. In a low-cost index tracker charging 0.07% a year, you’d end up with roughly £99,000. Now imagine the drag of an extra 1.5% a year — from active management fees, frequent trading costs, or bid-offer spreads on individual shares. You’d finish with about £66,000. Same market, same starting money, a third less wealth.
That 1.5% didn’t just cost you 1.5%. It cost you the compounding on that fee, every single year, for three decades. This is why index funds start every race with a built-in head start: they keep more of the market’s return in your pocket, automatically, forever.
The 2026 UK Starter Plan: Core and Satellite
So should beginners swear off individual stocks completely? Not necessarily. The approach that works for most people is called core and satellite:
- Core (about 90%): a global index tracker — something like a FTSE Global All Cap fund — inside a Stocks & Shares ISA. In 2026 you can shelter up to £20,000 a year, with all growth and withdrawals tax-free. This is the engine of your wealth. Set it, automate it, forget it.
- Satellite (about 10%): a small “learning account” for individual stocks. Buy shares in companies you genuinely want to understand. If your picks beat the index, wonderful — scale up slowly. If they don’t (likely at first), the damage is capped at a tenth of your money.
This plan does something clever: it lets you scratch the stock-picking itch without betting your future on it. And it produces your own personal evidence. After two years, compare your satellite’s return against your core. The numbers will tell you the truth no blog post can.
One more 2026-specific tip: automation beats willpower. Set the monthly payment into your ISA to leave your account the day after payday. You will never miss money you never saw.
FAQs
Index funds vs individual stocks: which should a beginner choose in 2026?
Beginners should choose index funds first. A single global index fund gives instant diversification across hundreds of companies for fees as low as 0.03–0.07% a year, and most professional stock pickers fail to beat the index over a decade. Keep your core boring, and use a small separate account if you’re curious about picking stocks.
How much money do I need to start investing in index funds?
You can start with as little as £25 a month into a Stocks & Shares ISA with most UK platforms. The wrapper matters more than the amount early on: in 2026 you can invest up to £20,000 a year in an ISA with all growth and withdrawals tax-free. Consistency beats lump sums for beginners.
Can index funds lose money?
Yes — index funds fall when the market falls, and drops of 20% or more happen every few years. What they almost never do is go to zero, because one fund holds hundreds of companies. Over any 10 to 15 year period in history, broad markets have always recovered and grown. Time in the market beats timing the market.
When should a beginner start buying individual stocks?
Start only after your index-fund core is running on autopilot inside your ISA, and limit stock picking to money you can afford to lose — around 10% of your portfolio. If you enjoy the research and your picks beat your index fund over two or three years, you can gradually increase the share. Most people never need to.
The Bottom Line
Index funds are the right answer for the overwhelming majority of beginners. They’re cheaper, simpler, and historically more rewarding than picking stocks. Give individual shares a small, separate corner of your portfolio if you’re curious — but let the haystack do the heavy lifting.
Beginners should choose index funds first. A single global index fund gives instant diversification across hundreds of companies for fees as low as 0.03–0.07% a year, and most professional stock pickers fail to beat the index over a decade. Keep your core boring, and use a small separate account if you’re curious about picking stocks.
You can start with as little as £25 a month into a Stocks & Shares ISA with most UK platforms. The wrapper matters more than the amount early on: in 2026 you can invest up to £20,000 a year in an ISA with all growth and withdrawals tax-free. Consistency beats lump sums for beginners.
Yes — index funds fall when the market falls, and drops of 20% or more happen every few years. What they almost never do is go to zero, because one fund holds hundreds of companies. Over any 10 to 15 year period in history, broad markets have always recovered and grown. Time in the market beats timing the market.
Start only after your index-fund core is running on autopilot inside your ISA, and limit stock picking to money you can afford to lose — around 10% of your portfolio. If you enjoy the research and your picks beat your index fund over two or three years, you can gradually increase the share. Most people never need to.