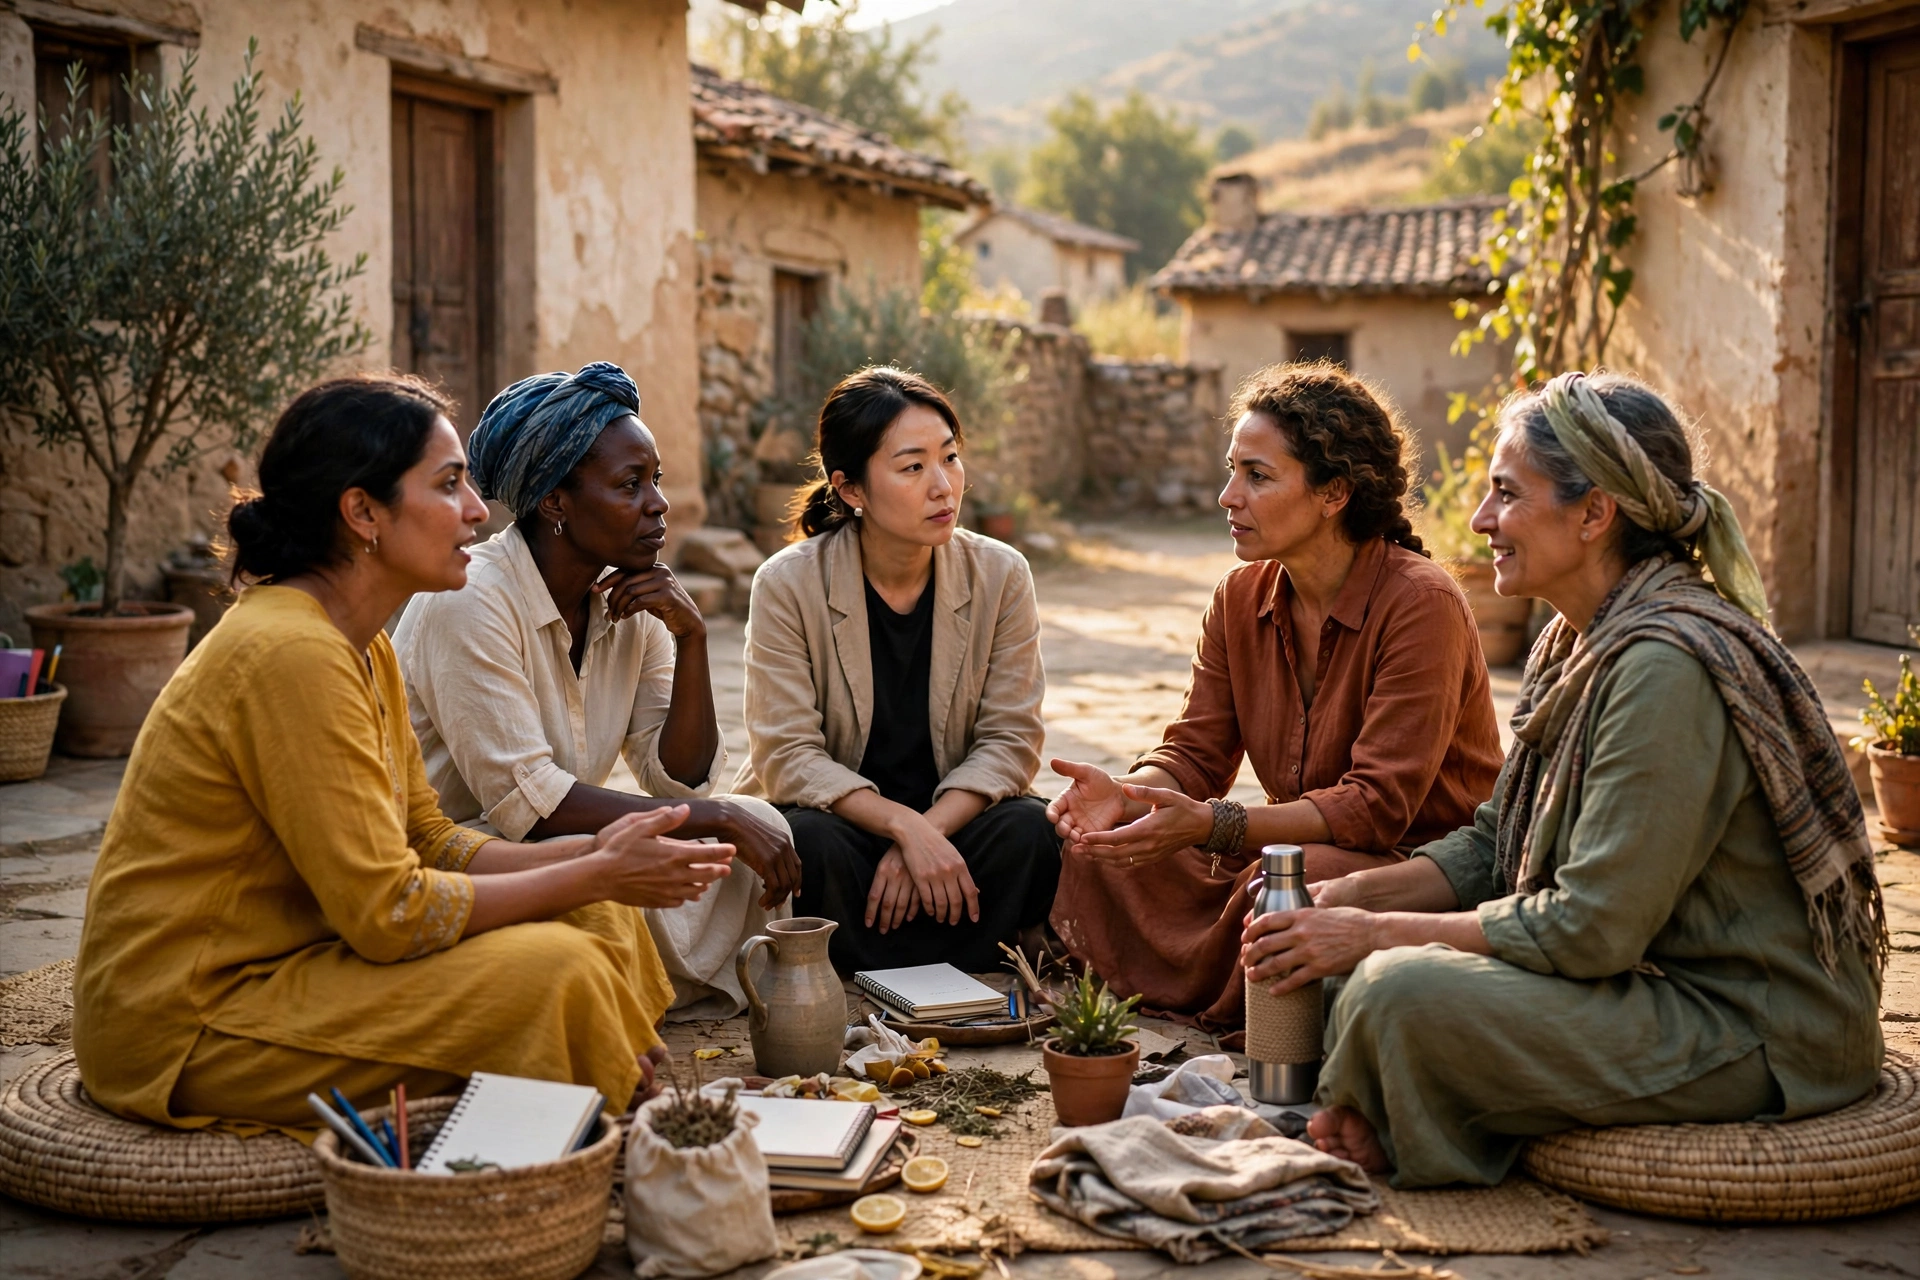
If you have ever wondered how people with no collateral, no credit history, and no bank account still manage to borrow money, the answer is often group lending microfinance. It is the model that made microfinance famous — the system pioneered in Bangladesh in the 1970s that went on to reach hundreds of millions of borrowers worldwide. And despite all the financial technology that has arrived since, it is still going strong in 2026.
The concept is beautifully simple: instead of lending to one person alone, the lender forms a small group of borrowers — usually five to ten people — who guarantee each other’s loans. If one member cannot pay, the others step in. No house deed, no guarantor with a salary slip — just social trust turned into financial collateral. But how does it actually work in practice? And is it right for you? Let us break it down.
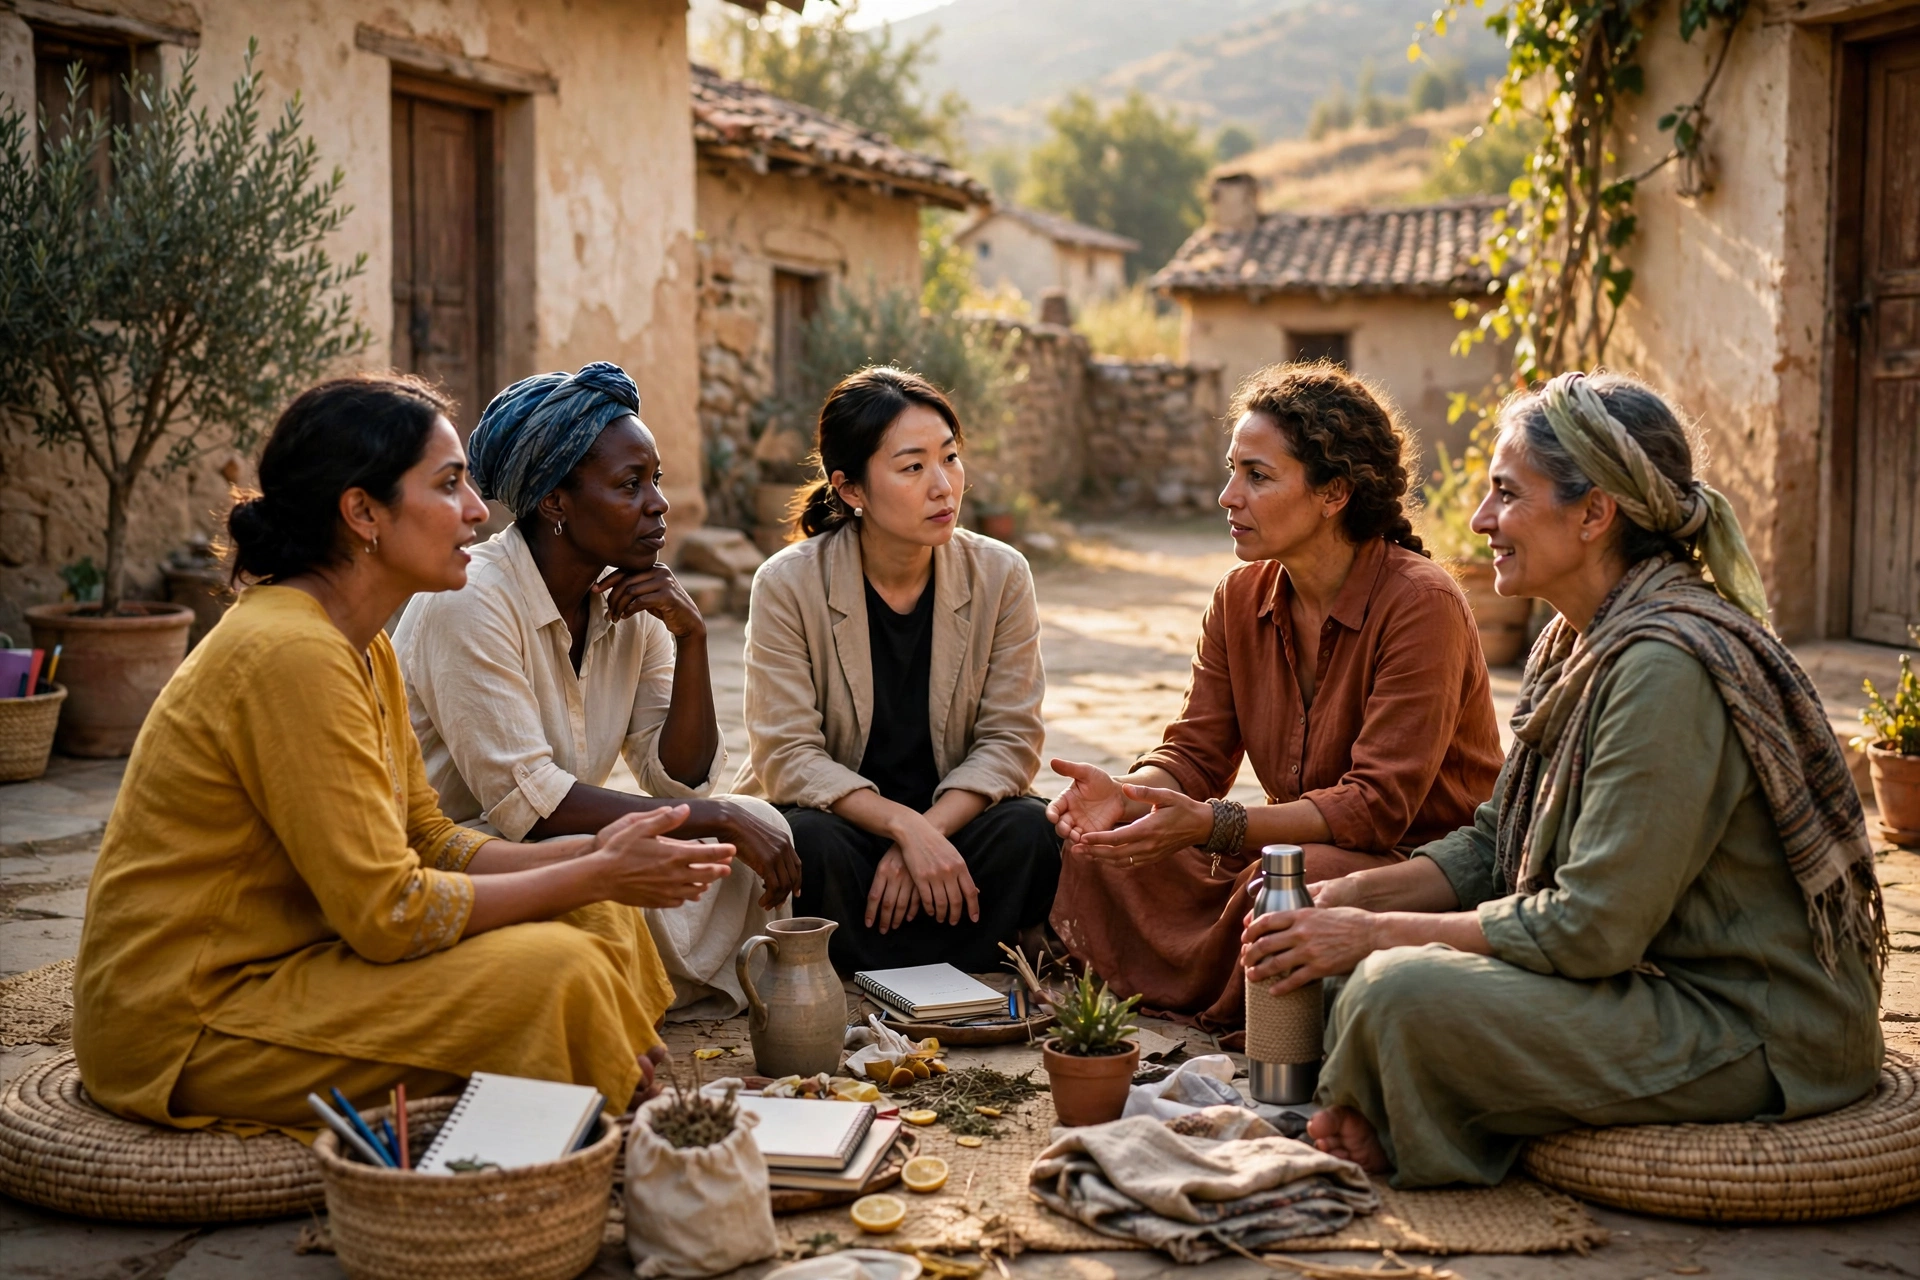
How Group Lending Microfinance Works Step by Step
The process usually starts with the lender organizing borrowers into a group, or approving a group that formed on its own. Most institutions require that members know each other and live in the same area — neighbors, fellow market traders, members of the same cooperative. This is deliberate: the lender is outsourcing the screening to the people who know you best.
Once the group is formed, each member applies for an individual loan, but the loans are linked. The group meets regularly — often weekly — with a field officer from the lending institution. At these meetings, members make their repayments publicly, discuss their businesses, and receive basic financial training. It is part bank branch, part business support group.
Here is the key mechanism: joint liability. If one member misses a payment, the rest of the group is expected to cover it. This does not mean the defaulter is off the hook — they still owe the money — but the group ensures the lender gets paid on time regardless. Because nobody wants to be the person who lets the group down, repayment rates in group lending programs are famously high, often above 95%.
Loans typically start small — perhaps $50 to $200 — and grow with each successful cycle. Repay your first loan cleanly, and your next one might be $300. Then $500. It is a ladder: the group proves its reliability, and the lender rewards it with bigger amounts.
The Benefits of Borrowing as a Group
Group lending solves problems that keep millions of people locked out of the financial system. Consider the advantages:
- No collateral required. Your reputation within the group replaces physical assets. For someone who owns little more than their tools and their trade, this is everything.
- Built-in accountability. It is much harder to skip a payment when five neighbors are sitting across from you at the weekly meeting. Social pressure, used constructively, keeps repayment discipline high.
- Peer support and learning. Group meetings are not just about money. Members share business tips, warn each other about bad suppliers, and sometimes even become each other’s customers. Many borrowers say the network is as valuable as the loan.
- Financial education. Lenders use the regular meetings to teach budgeting, record-keeping, and savings habits — skills that outlast any single loan.
- Faster access to larger loans. A clean group record builds trust quickly, so members can graduate to bigger loan amounts faster than they could alone.
There is also a quieter benefit: confidence. Many first-time borrowers say the group gave them the courage to start a business at all — walking into a financial arrangement with four friends changes the dynamic entirely.
The Downsides and Risks You Should Know
Group lending is not all sunshine. The same social pressure that keeps repayment high can turn toxic. When one member genuinely cannot pay — after an illness, a failed harvest, a robbery — the group still has to cover the amount. That can breed resentment, break friendships, and in extreme cases lead to members being publicly shamed at meetings.
There is also the free-rider risk: a less scrupulous member might borrow recklessly, knowing the group will bail them out. Lenders try to prevent this with careful group formation and progressive loan sizes, but it still happens.
Another limitation: the group moves at the pace of its slowest member.
And the time cost is real. Weekly meetings eat up hours of travel, waiting, and discussion — for a busy trader, that is money. Some borrowers eventually decide the meetings cost more than the loan is worth, especially as their businesses grow.
Group Lending vs. Individual Microloans
So which is better? It depends entirely on where you are in your borrowing journey. Group lending microfinance is ideal for first-time borrowers with no credit history and no collateral. The group substitutes for everything you lack on paper, and the structure teaches repayment discipline.
Individual microloans, by contrast, suit borrowers who have already proven themselves — maybe through one or two group cycles — and now want larger amounts, flexible schedules, and privacy. With an individual loan, your business decisions are your own, and nobody else’s problems become your problem.
Many lenders actually design their programs as a pathway: start in a group, build your record, graduate to individual lending. If you are offered this route, it is usually worth taking. The group phase is short, the lessons are real, and the individual loans on the other side are significantly more flexible.
Group Lending Microfinance FAQs
How many people are usually in a lending group?
Most groups have five to ten members, though some programs use larger groups of up to thirty. Smaller groups tend to work better because members know each other well and the social accountability is stronger.
What happens if one group member defaults?
The other members are expected to cover the missed payment so the lender is paid on time. The defaulter still owes the money — to the group, now — and repeated defaults can get a member expelled, while the rest of the group may face reduced future loan amounts.
Do I need collateral for a group loan?
No. That is the entire point of the model. The group’s joint liability replaces physical collateral, which is why group lending reaches people that conventional banks will not touch.
Can I leave the group once I join?
Usually yes, but typically only between loan cycles — not in the middle of one. Most lenders also require the group to find a replacement member or continue with fewer people. Check the terms before joining so there are no surprises.
Group lending microfinance remains one of the most powerful tools for financial inclusion ever invented. It turns community trust into credit and has funded millions of small businesses that banks would never have considered. It is not perfect — the social pressure can cut both ways, and growing businesses eventually outgrow it — but as a first step into borrowing, few systems work better.