Introduction
Starting or growing a small business takes money. That part is obvious. What is less obvious is where that money comes from when traditional banks say no — which is exactly where microfinance for small businesses comes in.
For millions of entrepreneurs around the world, the answer is microfinance. It is not charity, and it is not a shortcut. It is a practical set of financial tools — small loans, simple savings accounts, and honest guidance — built for people who are locked out of conventional banking.
In this guide, we will walk through what microfinance actually is, how microloans work in practice, how to budget for repayments without stress, and which free tools can help you plan before you borrow a single rupee or dollar.
What Is Microfinance for Small Businesses?
The term gets thrown around a lot, so let us be precise. Microfinance is a collection of financial services designed for individuals and small businesses that cannot access traditional banks. It usually includes four things:
- Microloans: Small loans, often ranging from $100 to $50,000, meant for starting or expanding a business. The amounts are modest, but for a small shop or a home-based business, they can be transformative.
- Microsavings: Simple savings accounts with no minimum balance and no confusing fee structures. The idea is straightforward: even tiny, regular deposits build a safety net over time.
- Microinsurance: Low-cost protection against the shocks that hit small businesses hardest — illness, crop failure, equipment breakdown, or a sudden drop in customers.
- Financial education: Perhaps the most underrated piece. Many microfinance institutions offer training on budgeting, bookkeeping, and basic business planning, because a loan without knowledge is a risk.
How Microloans Actually Work
Forget the image of a bank manager in a suit reviewing your collateral. Microloans work differently. Lenders care far more about your business idea, your cash flow, and your character than about the assets you own.
Here is what the process typically looks like:
- Application: You explain your business, what the money is for, and how much you need. Keep it honest and specific. “I need $2,000 to buy a second sewing machine and fabric for the next three months” beats “I need money for business” every time.
- Review: The lender looks at your business plan and, more importantly, your ability to repay. Some use alternative credit scoring — your mobile payment history or utility bills — instead of a traditional credit score.
- Disbursement: If approved, funds are released. Sometimes this happens in stages, tied to milestones, which actually protects you from taking on more than you can handle.
- Repayment: You pay back in small weekly or monthly installments, usually over 6 to 24 months. The rhythm of small, regular payments is deliberate — it keeps the loan manageable.
One warning: interest rates and fees vary enormously between lenders and regions. Always compare the total repayment amount, not just the monthly installment. A loan that looks cheap per month can be expensive overall.
Budgeting for a Microloan (Without the Headache)
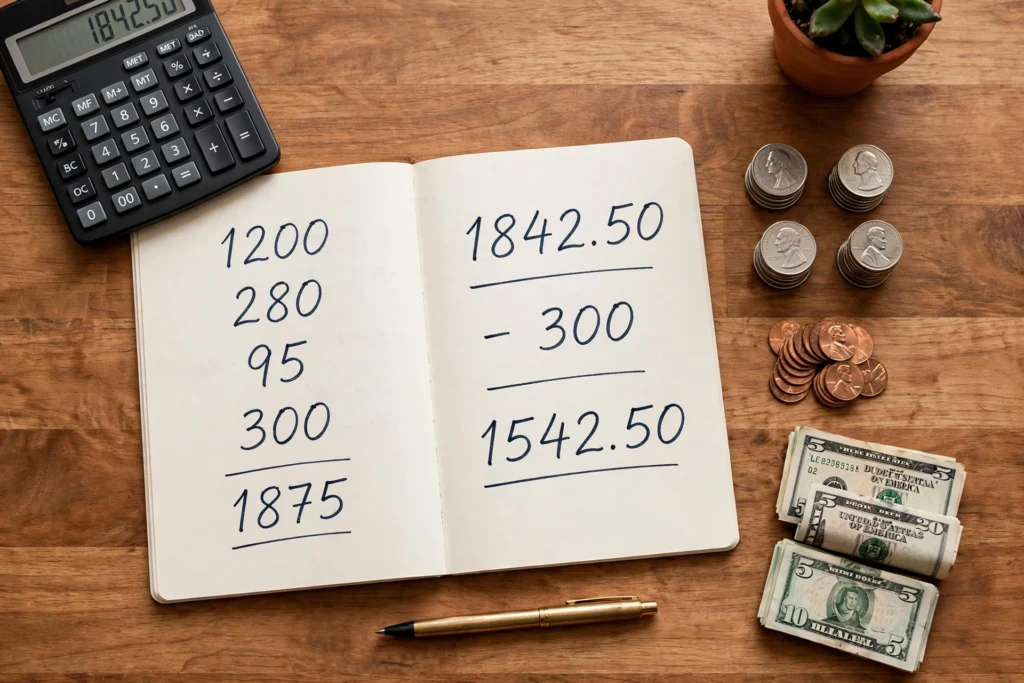
This is the step most people skip, and it is the step that matters most. Before you sign anything, build a simple budget on paper:
- Write down all your monthly business income — be realistic, use last three months as a guide.
- List every fixed cost: rent, salaries, supplies, transport.
- Add the expected loan installment to that list.
- Keep a 10–15% buffer for surprises, because surprises always come.
Now look at the numbers honestly. If they do not work on paper, they will not work in real life either. Borrow less, or wait until revenue grows. There is no shame in that — it is good business sense.
A free loan calculator is your best friend here. Plug in different loan amounts and terms, and see how the monthly payment changes. Ten minutes with a calculator can save you months of stress later.
What Do Small Businesses Actually Use Microfinance For?
The uses are as varied as small businesses themselves, but the most common ones are:
- Inventory and raw materials: Stocking up before a busy season without draining cash reserves.
- Equipment: A new oven for a bakery, a better laptop for a freelancer, tools for a workshop.
- Cash-flow gaps: Covering the quiet months when income dips but expenses do not.
- Expansion: Opening a second location, or finally setting up that online store.
- Emergencies: Fixing a broken refrigerator, repairing a delivery bike — the unglamorous stuff that keeps a business alive.
How to Improve Your Chances of Getting Approved
Lenders want to see that you are serious. You do not need a perfect record, but you do need to show effort:
- Keep records. Even a simple notebook with daily sales and expenses counts. Consistency matters more than fancy accounting software.
- Show steady revenue. Lenders love stability. Even small, regular income is reassuring.
- Start small. Take a modest first loan, repay it on time, and build trust. Your second loan will be easier.
- Consider group lending. In many regions, small groups borrow together and guarantee each other. If your individual history is thin, this can open doors.
Mistakes to Avoid
Let us be blunt about the traps:
- Overborrowing. The most common and most painful mistake. Borrow what your cash flow supports, not what you dream about.
- Ignoring the total cost. Compare annual percentage rates, processing fees, and the full repayment figure. Read the fine print, all of it.
- Mixing personal and business money. This is how small businesses quietly bleed. Separate your accounts from day one, even if it feels like extra work.
Free Tools That Make Planning Easier
You do not need expensive software to plan well. Free online tools cover the essentials:
- Loan calculators let you compare monthly payments across different lenders and terms in seconds.
- Compound interest calculators show how your savings grow over time — useful when deciding between saving up and borrowing.
- Budget planners help you track income and expenses without spreadsheets getting out of hand.
The habit of planning with numbers first is what separates a loan that grows your business from one that slowly strangles it.
Microfinance and Technology: A Quick Note
The microfinance world is changing fast. Mobile money has made disbursements and repayments dramatically easier in many countries. Some lenders now use alternative data — like your mobile top-up patterns — to assess creditworthiness. If you run your business partly through a phone, that digital footprint can actually work in your favor. For the bigger picture, the World Bank tracks global progress on financial inclusion.
Conclusion
Microfinance has helped millions of small businesses take their first real step — or their next big one. But the tool is only as good as the hands using it. Borrow wisely: understand the full cost, budget for every installment, and use free planning tools before you commit to anything.
Start with the numbers, stay honest about what you can afford, and let the loan serve the business — not the other way around. Explore our free microfinance calculators and guides, and plan your next move with confidence.
Microloans typically range from $100 to $50,000, depending on the lender and region. Start with a modest first loan that your cash flow clearly supports, repay it on time, and larger follow-up loans become easier to access.
Usually not. Microlenders focus more on your business plan, cash flow, and ability to repay than on assets. Some use group guarantees, where small groups borrow together and vouch for each other, instead of traditional collateral.
Overborrowing — taking more than the business cash flow can support. Always build a simple budget first: list income, fixed costs, and the expected loan installment, and keep a 10–15% buffer. If the numbers don’t work on paper, they won’t work in real life.
Yes — mixing personal and business money is one of the fastest ways a small business quietly bleeds cash. Use separate accounts so you can track the loan, see true business costs, and prove repayment capacity to lenders.