The APR vs AER difference UK savers and borrowers ask about boils down to this: APR measures the cost of borrowing over a year, while AER measures the return on savings over a year. APR makes debt look scarier the higher it goes; AER makes savings look better the higher it goes. Mixing them up can cost you real money.
You’ll see both acronyms splashed across adverts — card mailers, savings pages, even buses. Banks love them because they sound official. And for once, the comparison genuinely works — as long as you know which direction each one points.
What APR Actually Means
APR stands for Annual Percentage Rate: the headline yearly cost of borrowing. It isn’t just the interest — it folds in most compulsory charges, like loan arrangement fees, so you can compare a Barclays loan against a Tesco one on a roughly level playing field.
One catch: card adverts quote the “representative” APR — only 51% of accepted applicants need to get that rate or lower. With a patchy credit file you could be offered much more, which is why two neighbours can hold the “same” card at very different rates.
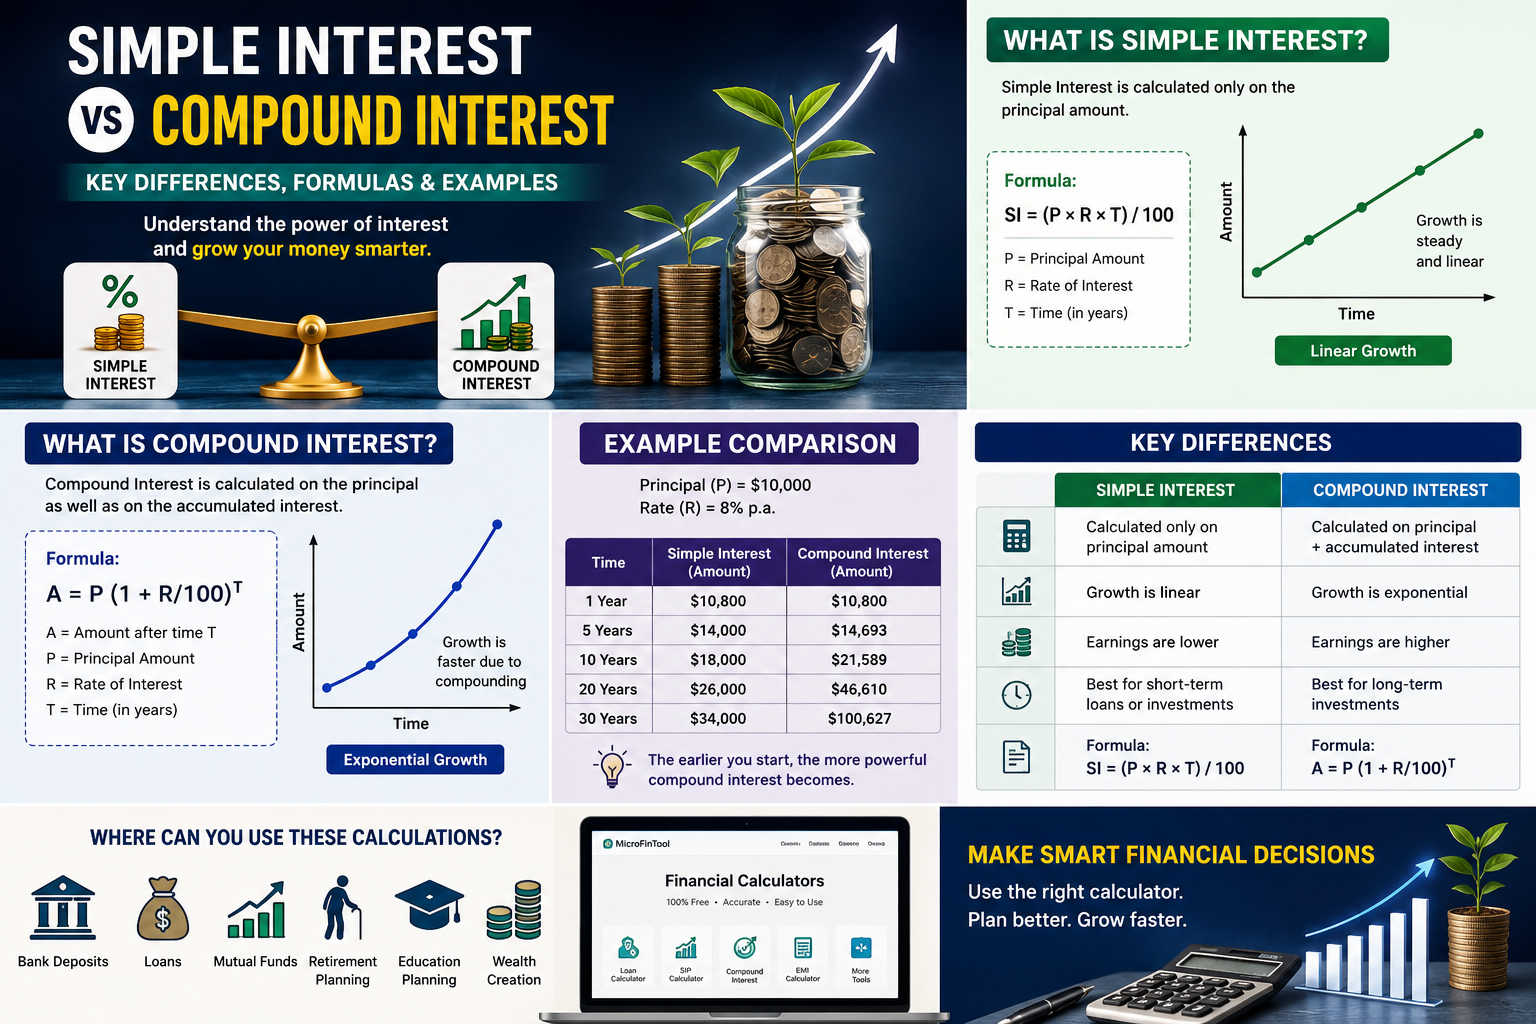
Card interest accrues daily, not yearly. So 24% APR doesn’t mean you simply pay 2% a month — unpaid interest starts earning interest of its own. Debt snowballs, which is why the worked example below is worth two minutes.
What AER Actually Means
AER is the Annual Equivalent Rate — the savings world’s answer to APR, pointing the other way. It shows what money in a savings account grows to over a full year if left completely alone, with interest compounding exactly as the account pays it.
So a 4.5% AER account turns £2,000 into £2,090 in twelve months. No tricks — but only if you withdraw nothing, the rate never changes, and every interest payment is added and starts earning its own interest. Break any of those and your real return drops.
The APR vs AER difference UK: Two Worked Pound Examples
Enough theory — let’s watch the APR vs AER difference UK borrowers and savers feel in their wallets, using £2,000 on each side.
Side one: borrowing. You put £2,000 on a card at 24% APR and make no repayments for a year. Monthly interest means a monthly rate of roughly 2%, so after twelve months of interest-on-interest you owe £2,000 × 1.0212 ≈ £2,536 — about £536 of interest. Notice it beats a flat 24% of £2,000 (£480)? That extra £56 is compounding working against you.
Side two: saving. You park £2,000 at 4.5% AER, untouched, for a year. Result: £2,090 — just £90 of interest. Same starting sum, wildly different outcomes: £536 lost versus £90 gained. That’s the brutal asymmetry of personal finance — borrowing rates run five or six times savings rates, and both compound.
So paying off a 24% card beats “saving” at 4.5% every time. No high-street account outruns that debt — the card gets paid first. Always.
Why AER Beats the Gross Rate When Interest Pays Monthly
This one trips up careful readers too. Some accounts quote a “gross rate” beside the AER — say 4.41% gross with 4.50% AER. The gross is the flat yearly rate before compounding; the AER is what you actually receive once monthly interest starts earning interest of its own.
Think of a snowball rolling downhill: monthly interest adds a fresh layer twelve times a year, and each layer rolls too. That extra roll is why the AER (4.50%) sits just above the gross (4.41%). Comparing accounts? Ignore the gross and match AER against AER — it’s the only number showing what lands in your pocket.
Common Confusions Cleared
- Can I compare APR with AER directly? No — the big one. APR prices borrowing; AER rewards saving. A 6% APR loan and a 6% AER account aren’t “equal and opposite” — fees, compounding and small print differ. Compare APR with APR, AER with AER.
- Does 0% APR mean free money? For the promo period, near enough — but the revert rate is often 24%+. Miss the deadline and the snowball starts.
- Why is my card APR higher than my mortgage APR? Unsecured revolving credit is riskier for lenders; a mortgage is secured on your home. Different risk, different price.
- What happens to my AER if I withdraw? Easy-access accounts just pay interest on the lower balance afterwards. Fixed-term accounts can be harsher — slashed rates or penalties. Check before you dip in.
FAQs
What is the simplest way to remember the APR vs AER difference UK beginners keep mixing up?
The simplest way to remember the APR vs AER difference UK savers and borrowers face: APR is the price you pay to borrow, AER is the reward you get for saving. APR punishes, AER rewards. Attached to a card or loan? It’s APR. Attached to a savings account? It’s AER.
Is a higher APR ever good?
A higher APR is never good for the borrower — it directly means pricier debt. The only “good” high number is a high AER on savings. Between debts the lower APR usually wins, though still check fees, since APR already includes most compulsory charges.
Why do banks advertise AER instead of the monthly interest rate?
Banks advertise AER so savers can compare accounts fairly whatever the payout rhythm — monthly, quarterly or yearly. AER folds compounding frequency into one annual figure, so monthly-paying and yearly-paying accounts can be judged side by side on what your savings actually earn.
Does APR include all the fees I’ll pay?
APR includes most compulsory charges — arrangement fees plus the interest — making it the fairest way to compare loans. It excludes optional extras like payment-protection insurance or late-payment penalties, so read the representative example and small print before signing.
Can my savings AER change after I open the account?
Yes — on easy-access and variable-rate accounts the bank can change your AER with notice, and rates often drop once an introductory bonus ends. Fixed-term accounts lock your AER for the whole term, so the return is guaranteed unless early withdrawal triggers a penalty.
So: APR is what borrowing costs you, AER is what saving earns you, and the two should never be confused. The APR vs AER difference UK households wrestle with is a reminder to look at both sides of your money — kill expensive debt before chasing modest savings returns, and always compare like with like. Get those habits right and the acronyms start helping instead of intimidating.
The simplest way to remember the APR vs AER difference UK savers and borrowers face: APR is the price you pay to borrow, AER is the reward you get for saving. APR punishes, AER rewards. Attached to a card or loan? It’s APR. Attached to a savings account? It’s AER.
A higher APR is never good for the borrower — it directly means pricier debt. The only “good” high number is a high AER on savings. Between debts the lower APR usually wins, though still check fees, since APR already includes most compulsory charges.
Banks advertise AER so savers can compare accounts fairly whatever the payout rhythm — monthly, quarterly or yearly. AER folds compounding frequency into one annual figure, so monthly-paying and yearly-paying accounts can be judged side by side on what your savings actually earn.
APR includes most compulsory charges — arrangement fees plus the interest — making it the fairest way to compare loans. It excludes optional extras like payment-protection insurance or late-payment penalties, so read the representative example and small print before signing.
Yes — on easy-access and variable-rate accounts the bank can change your AER with notice, and rates often drop once an introductory bonus ends. Fixed-term accounts lock your AER for the whole term, so the return is guaranteed unless early withdrawal triggers a penalty.