If you’ve ever stared at a pile of unpaid invoices and an empty bank account in the same week, you’re not alone. Here’s what most courses skip: cash flow management small business owners practise matters more than profit on paper. You can be “profitable” and still go broke if money lands after the rent is due. For freelancers, stall holders, and home-based shops, cash flow decides whether you can buy stock on Monday.
Take Maria, who sells handmade candles at a Leeds Saturday market. She makes about £800 a month — but supplies cost £250 upfront and her £120 pitch fee is due in advance. Spend all December’s takings on Christmas stock, and January’s bills leave her stuck. That’s a cash flow problem, not a profit problem. Let’s fix it — for good.
Why Cash Flow Management Small Business Owners Need Comes First
Profit tells you whether your business model works. Cash flow tells you whether you survive the month — and they can disagree wildly. Why? Timing. Your client pays in 30 days, but the electricity bill is due this Friday. That gap is what kills tiny businesses.
Picture a freelance designer in Ohio landing a $4,000 project. Brilliant — except payment arrives 45 days after delivery, while $600 rent and groceries are due this week. She’s owed money, but you can’t pay rent with an invoice. Cash on hand wins the waiting game, not the biggest invoice pile.
Running out of cash is a top reason small firms shut down. The fix needs no accounting degree — just a twenty-minute weekly habit.
Track Your Money In and Out (the 20-Minute Weekly Habit)
Forget complicated software. Open a free spreadsheet (Google Sheets) or a notebook, and make two columns: Money In and Money Out. Every Friday, log everything.
- Money In: every payment that actually landed — card sales, transfers, cash. Not invoices you sent.
- Money Out: every expense you paid — stock, rent, supplies, fuel, subscriptions.
- The balance: what’s left. Then glance at what’s due next week.
This single habit is the heart of cash flow management small business owners can actually sustain — because surprises vanish. You’ll never again learn, three days too late, that your card fees and stall rent came out on the same day.
Keep business money separate
Use one business account so personal and business money never mix. When spending blurs, your cash picture turns to fog — and fog is where problems hide.
Deal With Late Payments Before They Sink You
Late payments are the silent killer. In the UK alone, small firms are owed billions in overdue invoices. A photographer in Manchester waiting 60 days on £1,200 while £400 of studio rent looms — that’s daily reality for thousands.
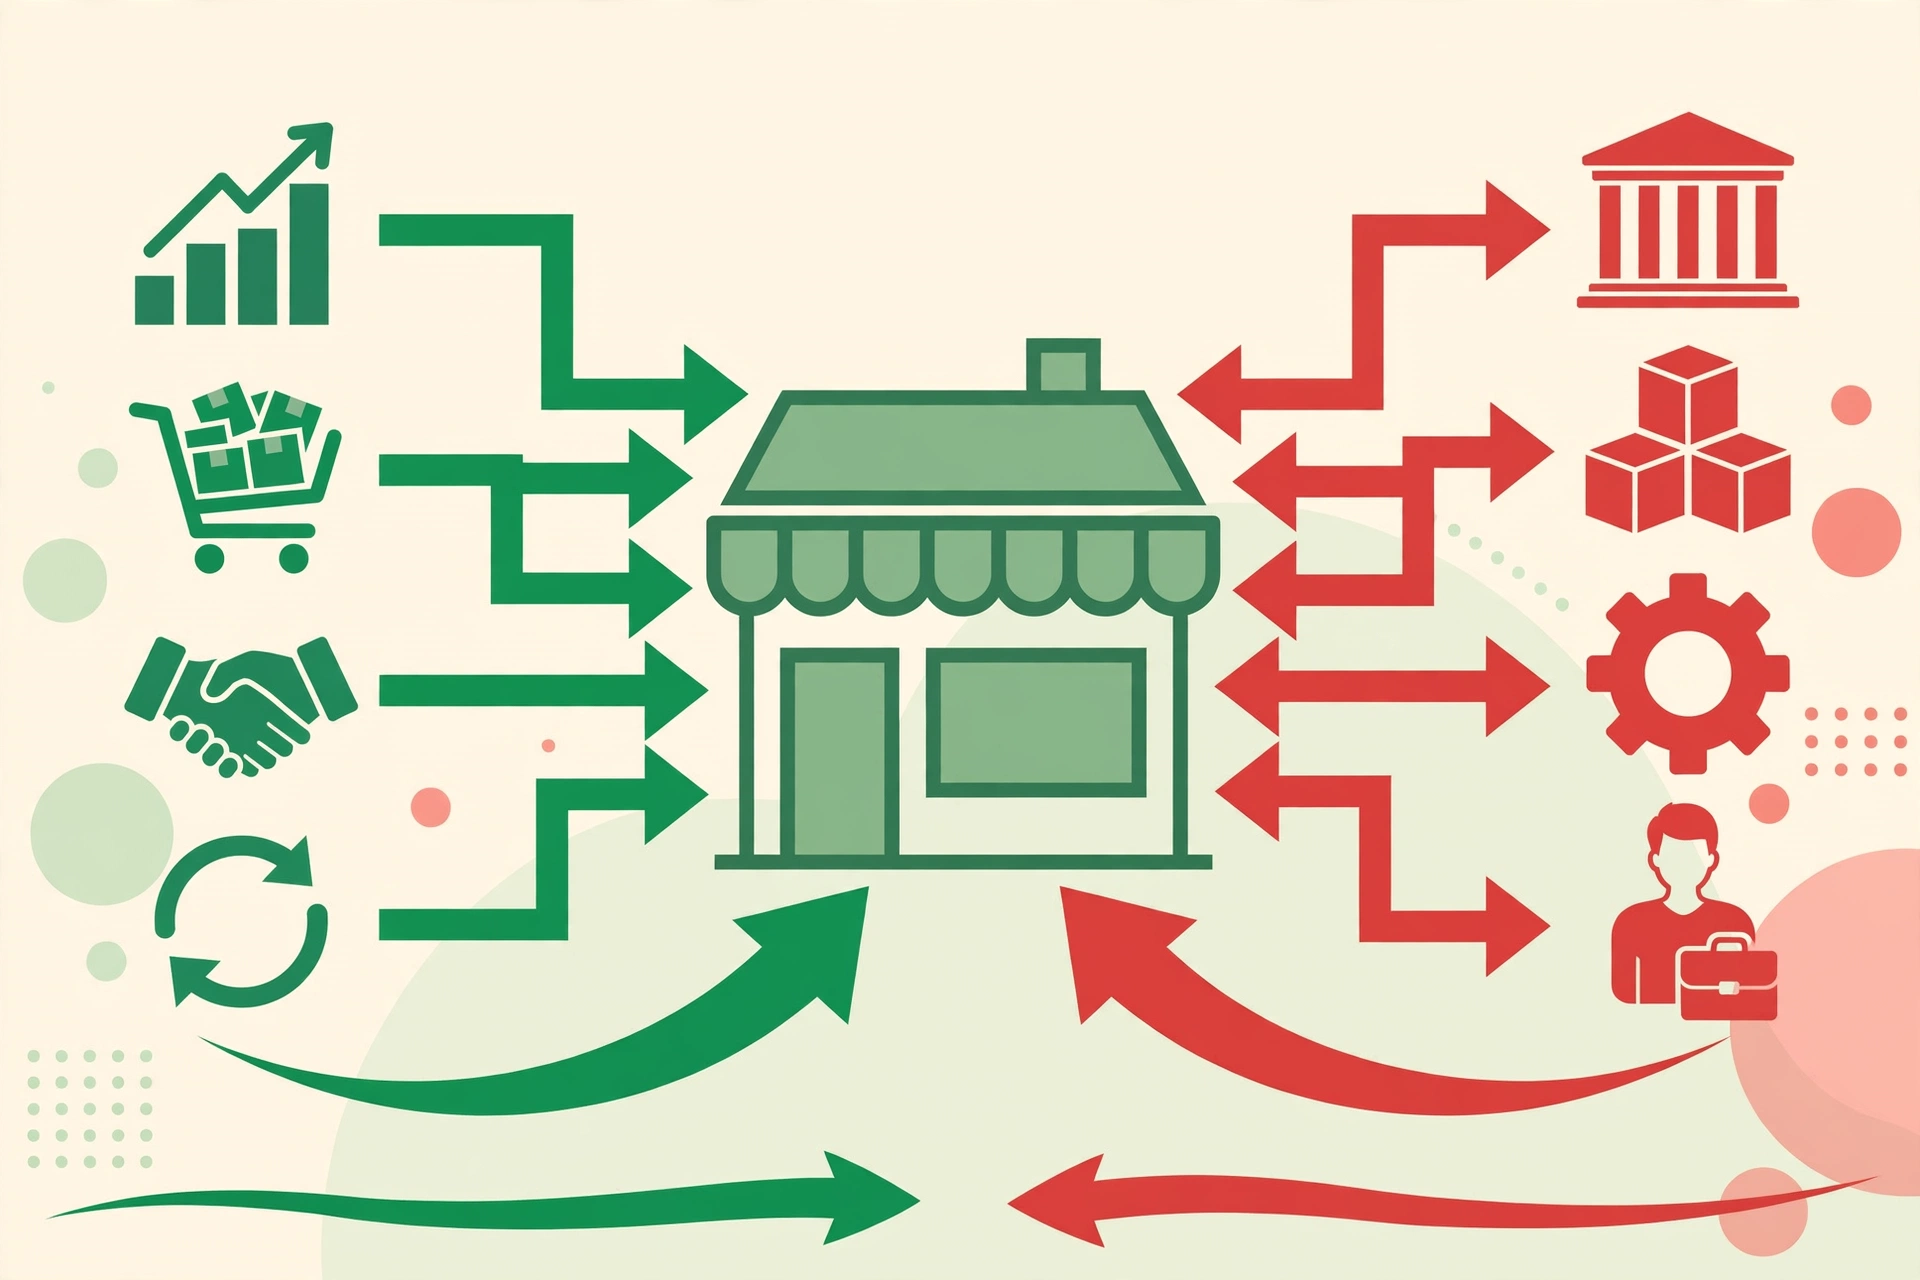
- Shorten your terms. Don’t default to “30 days.” Ask for 14 days, or a 30% deposit up front. Many clients simply agree.
- Invoice the day the work is done. Every day you delay sending the invoice is a day added to your wait.
- Automate reminders. A polite “just checking this landed” on day 15 beats an awkward phone call on day 45. Tools like Wave or Zoho Invoice do it free.
- Charge for lateness. UK firms are legally entitled to statutory interest (8% over the Bank of England base rate) on overdue commercial invoices — mentioning it in your terms often speeds things up.
Chasing payments isn’t rude — it’s your business breathing. The companies you invoice have whole departments for this; you shouldn’t feel awkward about a template email.
Build a Small Buffer (Your Business’s Airbag)
Even with perfect tracking, surprises happen — the oven breaks, a client vanishes, January is always slow. You need a buffer: a small pile of cash for emergencies only.
How much? Forget the textbook six months of expenses — most tiny businesses can’t park that much. Start with one month of essentials: if rent, stock, and bills come to €1,500, aim for €1,500 set aside, and grow it when you can.
Move 5–10% of every payment into a separate savings pot before you spend anything. A florist in Lyon stashing €40 from each wedding booking hits €1,000 after 25 weddings — without feeling the pinch in any single week.
Forecast Three Months Ahead (It’s Easier Than It Sounds)
Forecasting just means asking: “Roughly what’s coming in and out over the next three months?” A Texas home-baker knows December is huge and February is dead; an Amsterdam trader knows summer footfall doubles. Write it down, month by month:
- Expected income — be conservative, not hopeful
- Known expenses — rent, subscriptions, supplier orders, tax dates (the UK’s January self-assessment deadline trips up thousands)
- The running total — which month looks thin?
Spotted a thin month? Act now, not then: order less stock, push a promotion, chase invoices early. A forecast turns a future crisis into a present to-do list.
Frequently Asked Questions
What’s the difference between profit and cash flow?
Profit is revenue minus expenses on paper — including invoices you haven’t been paid for yet. Cash flow is actual money moving in and out. A business can show profit and still run out of cash if customers pay slowly while bills fall due immediately.
How often should a tiny business check its cash flow?
Weekly is the sweet spot. Monthly is too slow; daily is overkill unless cash is critically tight. Pick one day (Friday morning with a coffee) and stick to it for three months until it’s automatic.
What tools do I need for cash flow management?
A free spreadsheet is enough to start. Later, free tools like Wave (accounting) or Zoho Invoice (invoicing) can automate reminders. Don’t pay for expensive software early — the habit matters more than the tool.
How do I handle a big late payment when bills are due now?
Chase it firmly today — call, don’t just email. Ask providers about short extensions before deadlines; many grant them. Dip into your buffer — that’s what it’s for — then rebuild it. And never let one client owe you so much that their lateness becomes your crisis.
Conclusion
Here’s the whole game in one sentence: know what’s coming in, know what’s going out, and never let a surprise decide for you. Start this Friday — twenty minutes, two columns, one honest look at your money. Chase invoices the day they’re due, tuck away a little from every payment, and peek three months ahead. Cash flow management small business owners do consistently isn’t glamorous, but it’s the difference between surviving and merely looking profitable on paper.