Price too high and customers walk past. Price too low and you work yourself into the ground for nothing — or worse, customers assume your product is cheap rubbish. Pricing is the single decision that touches everything: your revenue, your brand, your sanity.
And yet most small business owners set prices by gut feeling, by copying a competitor, or by adding “a bit” to their costs and hoping. There’s a better way. Here’s how to price your products in 2026 — a practical method that works whether you sell candles in Leeds, software in Austin, or olive oil in Andalusia.
How to Price Your Products: Start With Your True Costs
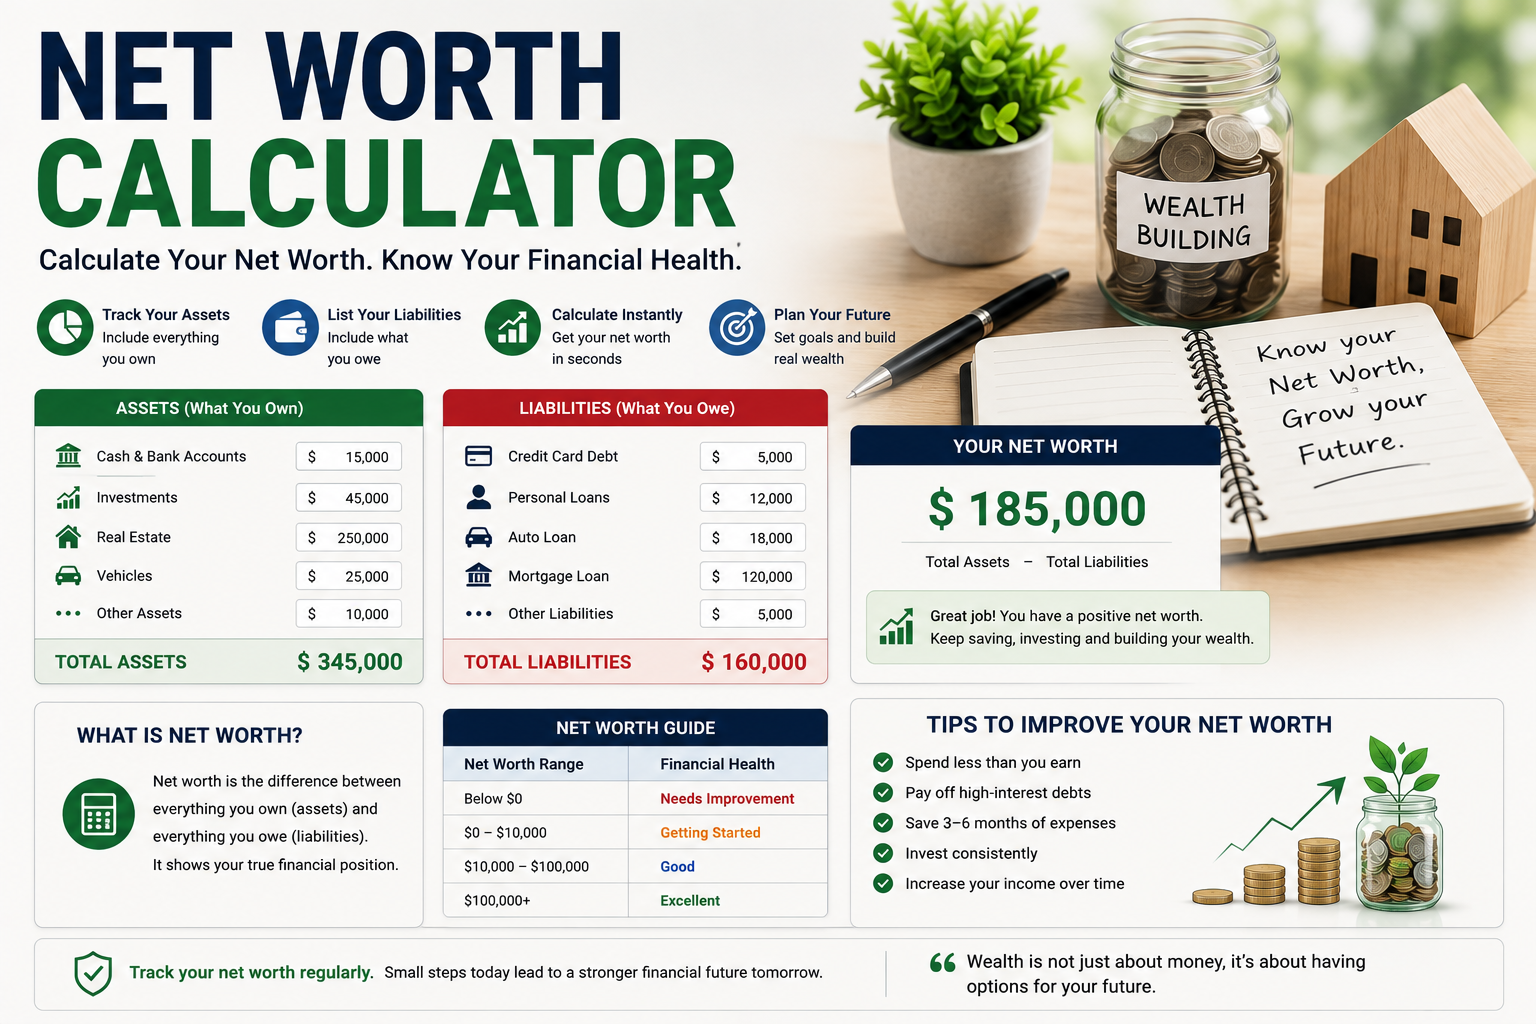
You can’t price profitably if you don’t know what things cost. And most small businesses underestimate. Your true cost per unit includes:
- Direct costs: materials, ingredients, packaging — everything physically in the product
- Labour: your time, valued honestly. If it takes you two hours and you’d pay someone £12/hour, that’s £24 — even if “it’s just you”
- Overheads: the sneaky ones. Market stall fees, website costs, payment processing (2–3% per sale), delivery, insurance, a share of your phone and internet
Add them up for one unit. That number is your floor — sell below it and you’re paying customers to take your products. Write it down; you’ll need it.
The Three Pricing Strategies (And When to Use Each)
1. Cost-plus pricing: simple and safe
Price = total cost × (1 + margin). A handmade soap costing £3.20 all-in, sold at £8, gives you a 60% margin. Cost-plus is honest and easy — perfect for physical products when you’re starting out. Its weakness: it ignores what customers would actually pay.
2. Competitor-based pricing: know your lane
Research 5–10 competitors selling similar products. Where do you sit — budget, mid-range, premium? Price deliberately relative to them. This works well in crowded markets (Etsy, Amazon, local markets) but beware the race to the bottom: competing only on price is a game small businesses lose.
3. Value-based pricing: charge for the outcome
What is your product worth to the buyer? A wedding cake isn’t flour and sugar — it’s the centrepiece of someone’s biggest day. A business consultant’s report isn’t hours — it’s the decision it enables. Value-based pricing captures the most profit but demands the most confidence and the best marketing.
The practical answer for most small businesses: start with cost-plus to guarantee you never lose money, check competitors to stay in a sensible range, then nudge toward value-based as your brand and reviews grow.
The Simple Pricing Formula That Actually Works
Here’s a step-by-step you can do tonight with a calculator:
- Calculate true unit cost (materials + labour + overhead share). Say: £4.50.
- Choose your target margin. Retail products typically need 50–70% gross margin to survive; services often target 60–80%. Let’s use 60%.
- Price = cost ÷ (1 − margin). £4.50 ÷ 0.40 = £11.25. Round to a clean £11.99 or £12.
- Sanity-check against competitors. If similar products sell at £9–14, you’re in the zone. If everyone charges £6, either your costs are too high or you need a premium story.
- Test and adjust. Raise prices 10% for new customers and watch. If conversion barely moves, your price was too low.
Pricing Psychology: Small Tweaks, Real Money
- Charm pricing: £9.99 outsells £10.00 — the effect is small but real, and it costs nothing.
- Anchor high: show a premium option first. A £45 “deluxe” bundle makes the £28 standard look reasonable.
- Bundle: “3 for £25” raises average order value and moves stock faster than discounting singles.
- Never apologise for prices. Discounts train customers to wait for sales. Instead of cutting prices, add value — free gift wrap, a handwritten note, faster delivery.
- Raise prices regularly. Costs rise every year; if your prices don’t, your margin silently dies. A 3–5% annual increase is normal and expected.
The Mistake That Kills Small Businesses: Underpricing
Let’s talk about the elephant in the room. New sellers chronically underprice — from insecurity (“who would pay that for my stuff?”), from copying the cheapest competitor, or from forgetting their own labour.
Underpricing doesn’t just hurt your wallet. It attracts bargain-hunters who haggle and leave bad reviews over pennies, while repelling quality customers who equate price with quality. And it’s brutally hard to raise prices later once customers anchor on “cheap.”
If you’re nervous, remember: you can always run a promotion, but you can rarely undo a reputation for being cheap.
FAQ: How to Price Your Products
What is a good profit margin for a small business product?
Aim for at least 50% gross margin on physical products (price minus direct costs, divided by price) — retail realities like fees, returns and slow months eat the rest. Services should target higher, typically 60–80%.
Should I match my competitors’ prices?
Match their range, not their exact price. If you’re better quality, price 10–20% above and explain why. If you’re new and unproven, price slightly below — but never at a loss.
How often should I raise my prices?
Review pricing at least once a year, and raise when costs rise or demand clearly exceeds supply (waiting lists, constant sell-outs). Small, regular increases beat rare shocking ones.
How do I price digital products with no material costs?
Use value-based pricing: what problem does it solve, and what is that worth? Research comparable products, then price on the transformation you deliver — not the zero cost of duplication.
Conclusion
Learning how to price your products comes down to three disciplines: know your true costs cold, position deliberately against competitors, and price on value as your reputation grows. Get the formula right once, review it yearly, and resist the urge to compete on price alone. Your products are worth what the right customers will happily pay — your job is to find that number and stand behind it with confidence.