If you run a business in the UK and you’re Muslim, there’s a question that tends to surface every year around Ramadan: do I owe zakat on my business — and if so, how on earth do I work it out? Between stock on the shelves, money in the till, invoices waiting to be paid and suppliers breathing down your neck, it can feel overwhelming. It isn’t, once you break it down. This guide walks you through exactly how zakat applies to business assets in Britain, with a full worked example in pounds.
A quick note: this covers the general principles, not a fatwa — for complex situations, ask a qualified scholar.
Does a UK Business Owner Actually Owe Zakat?
Yes, if three conditions are met. You’re Muslim, your zakatable wealth reaches the nisab threshold, and you’ve held it for one lunar (Hijri) year. That’s it. There’s no exemption for being “just a small business” — a corner shop in Bradford and a consultancy in London follow the same rules.
What surprises many owners is that zakat isn’t calculated on profit. It’s calculated on qualifying assets you hold on your zakat anniversary date. A business can have a slow year and still owe zakat, because the stock sitting in the warehouse counts even if sales were poor.
Which Business Assets Count — and Which Don’t
Think of it this way: anything you hold with the intention of selling it is zakatable. That includes:
- Stock and inventory — finished goods, raw materials, and work in progress, valued at their current wholesale (not retail) price.
- Cash — money in the business bank account, the till, and even cash you’ve set aside for the business at home.
- Receivables — money customers owe you, provided you realistically expect to be paid. A solid invoice counts; a debt from three years ago that you’ll never recover doesn’t.
And what doesn’t count? The things you use to run the business rather than sell: your shop fixtures, the delivery van, your laptop, machinery, and the shop premises itself. Personal belongings — your home, your car, your clothes — are never zakatable either.
A quick note for limited companies
If your business is a Ltd company, each shareholder calculates zakat on their share of the company’s zakatable assets — their proportion of stock, cash and receivables. Many UK accountants who work with Muslim clients will prepare a simple zakat balance sheet for you.
The Nisab Threshold in Pounds
Nisab is the minimum level of wealth that makes zakat obligatory. It’s defined in classical terms: 87.48 grams of gold or 612.36 grams of silver. Scholars differ on which one to use, and this genuinely matters because the two give very different numbers.
To convert to pounds, multiply by the current price per gram. As an illustration only — always check the live price on your zakat date — if gold were £75 a gram, the gold nisab would be about £6,560. If silver were 90p a gram, the silver nisab would be about £550. That’s a huge gap, which is why many UK scholars advise using the silver nisab: it’s the more cautious option, and it means more wealth circulates to those in need.
Pick one measure, note the date, and use it consistently each year.
Worked Example: Ayesha’s Boutique in Birmingham
Let’s make this concrete. Ayesha runs a modest fashion boutique. Her zakat anniversary falls in Ramadan, so she sits down with her stock list and bank statements. Here’s her calculation:
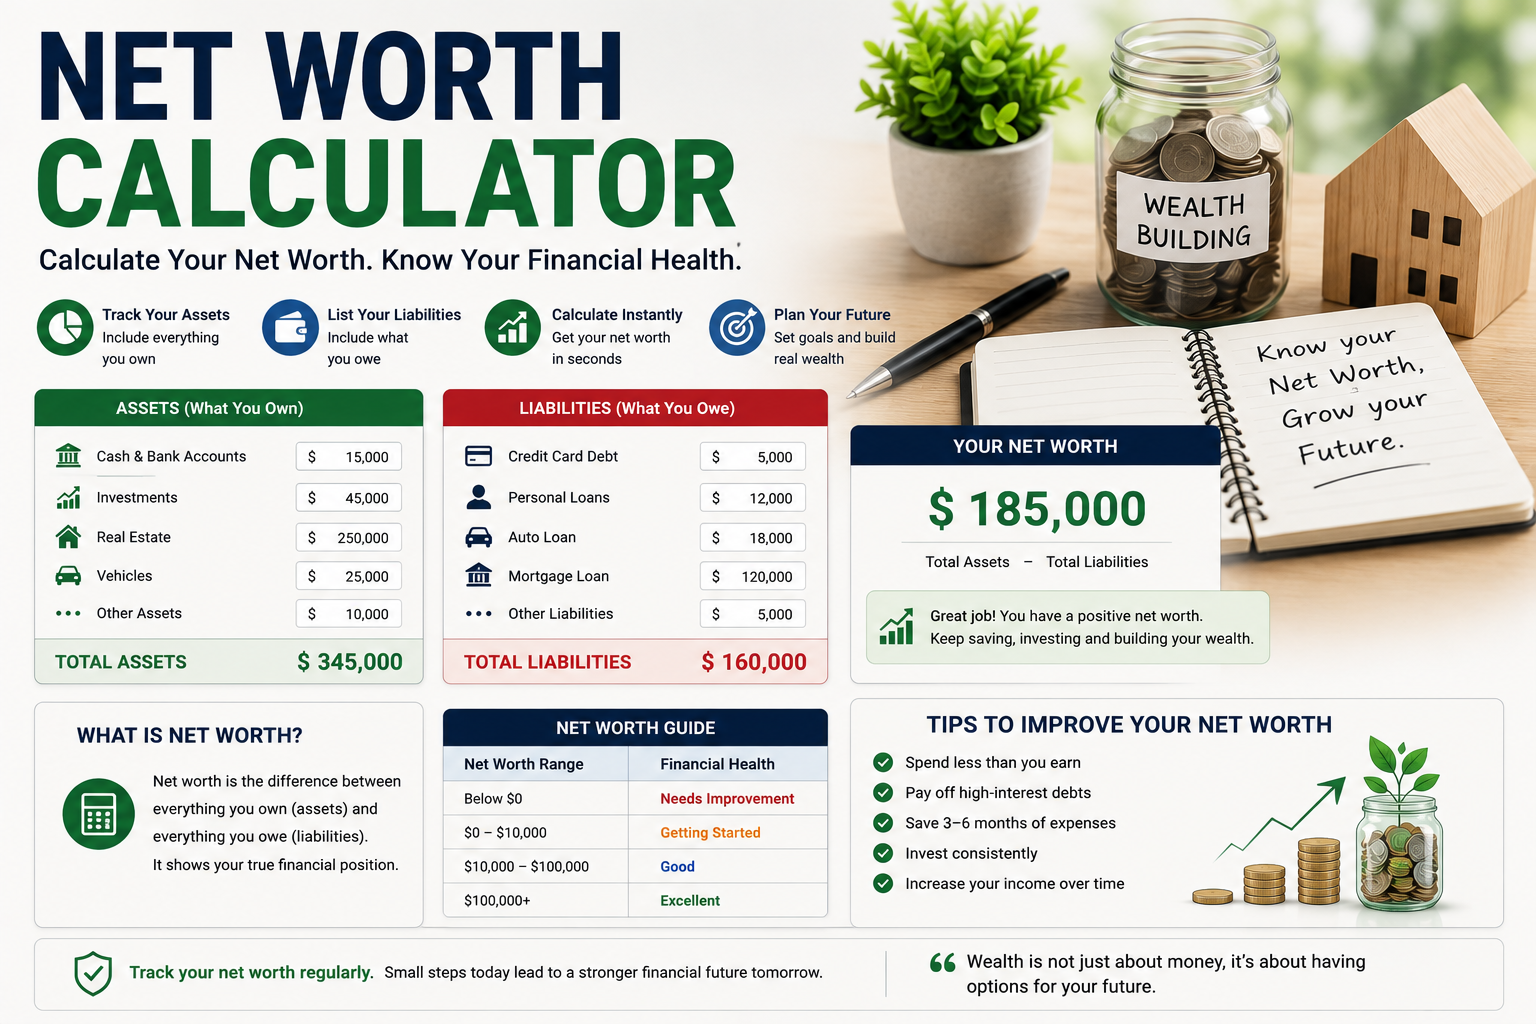
Step 1 — Add up zakatable assets (at current wholesale value):
- Stock on shelves and in storage: £18,000
- Cash in the business account and till: £4,500
- Customer invoices expected to be paid: £2,000
- Total zakatable assets: £24,500
Step 2 — Subtract short-term debts:
- Supplier invoice due next week: £3,000
- Business loan instalment due this month: £1,500
- Total deductible debts: £4,500
Step 3 — Check against nisab and calculate:
- Net zakatable wealth: £24,500 − £4,500 = £20,000
- £20,000 is well above either nisab measure, so zakat is due.
- Zakat = 2.5% × £20,000 = £500
That’s the whole process: assets, minus immediate debts, times 2.5%. Ayesha keeps a simple spreadsheet, so next Ramadan takes twenty minutes, not two days.
What About Debts?
Deduct debts due now or soon — next week’s supplier invoice, this month’s loan instalment. Don’t deduct a whole five-year loan balance, only the portion due. If debts pull your net wealth below nisab, no zakat is due that year.
Paying Your Business Zakat in the UK
Paying in Britain is straightforward. Most owners pay during Ramadan, though zakat is technically due on your lunar anniversary. Popular UK routes:
- National Zakat Foundation (NZF) — collects zakat in the UK and distributes it to Muslims here, with a dedicated business zakat calculator on their website.
- Islamic Relief UK and Muslim Hands — long-established charities accepting zakat for international relief work.
- Direct payment — giving straight to eligible individuals you know, which is perfectly valid and sometimes the most impactful.
Pay by bank transfer so you have a record, and pay promptly once calculated.
Common Mistakes to Avoid
- Valuing stock at retail price. Use what it cost you (wholesale), not what you’d sell it for.
- Forgetting receivables. Money owed to you is wealth — include it if you’ll realistically receive it.
- Including the van and fixtures. Tools of the trade aren’t zakatable.
- Leaving it until “things improve.” Zakat is due on what you hold, not on whether the year felt profitable.
Frequently Asked Questions
Do I pay zakat on my shop building or delivery van?
No. Fixed assets you use to run the business — premises, vehicles, machinery, fixtures — are not zakatable. Only trade goods, cash and recoverable receivables count.
My stock is worth less than I paid for it. Which value do I use?
Use its current wholesale value on your zakat date, not what you originally paid. If the market dropped, your zakat drops with it.
Can I give my business zakat to the National Zakat Foundation?
Yes. NZF accepts business zakat and distributes it to eligible Muslims within the UK. Many owners find this the simplest compliant route.
Do I have to calculate in Ramadan?
No — your zakat date is one lunar year after you first reached nisab. Many UK Muslims choose Ramadan for convenience and the multiplied reward, but any consistent Hijri date works.
Final Thoughts
Zakat on a business looks intimidating, but it’s one formula: add up what you hold to sell, subtract what you immediately owe, check against nisab, pay 2.5%. Do it once properly with a spreadsheet and every year after is routine. This Ramadan, set aside an afternoon, run your numbers, and pay with confidence.