For almost any borrowing beyond a few days, a credit card is cheaper than an overdraft in the UK. Arranged overdrafts typically charge 39.9% EAR with interest starting from day one, while a standard credit card charges around 24.9% APR — and costs nothing at all if you clear the balance in full each month. But “almost” matters, so let’s settle the overdraft vs credit card UK question properly, with real numbers for three borrowing scenarios.
Most people never actually compare the two. They just drift into whichever one their bank put in front of them — and banks, not coincidentally, put the 39.9% option front and centre.
Overdraft vs Credit Card UK: The One Difference That Decides Everything
Forget the headline rates for a moment. The decisive difference is when interest starts.
With an overdraft, you’re borrowing the instant your balance goes below zero. Interest accrues daily on whatever you’re overdrawn, from day one, at around 39.9% EAR on most mainstream UK current accounts. There’s no grace period, no interest-free window — just a meter running.
With a credit card, purchases typically get up to 56 days interest-free. Spend £500 on the 1st, get your statement, pay in full by the due date — and you’ve borrowed £500 for up to two months at literally zero cost. The interest only starts if you don’t clear the balance.
That single difference explains the whole verdict: credit cards reward discipline with free borrowing; overdrafts charge everyone from the first day. Now let’s see what that means in pounds.
Scenario 1: £200 Needed for 5 Days
Your car needs an urgent repair three days before payday. You need £200, briefly.
Overdraft: £200 at 39.9% EAR for 5 days costs under £1.10 in interest. Pocket change — but note it still costs something.
Credit card: put £200 on the card, repay in full on payday. Interest: £0.
Winner: the credit card on cost — but honestly, for tiny short gaps, convenience decides. If the overdraft is already arranged and the card is in a drawer, the £1.10 isn’t worth agonising over. Just don’t let “a few days” become a habit.
Scenario 2: £2,000 Carried for 6 Months
This is where the gap becomes a chasm. Say an emergency bill forces you to borrow £2,000 and you can only repay it gradually over six months.
Overdraft: £2,000 sitting in a 39.9% EAR overdraft for six months racks up roughly £350 in interest. That’s £350 for the privilege of borrowing your own bank’s money.
Standard credit card: the same £2,000 carried at 24.9% APR costs roughly £240–£250 in interest over six months. Still painful, but about a third cheaper than the overdraft.
0% purchase credit card: move the planned spending to a 0% purchase deal (12–24 months interest-free is common for new customers) and the interest bill is £0. You just repay £2,000 over six months.
Winner: the 0% purchase card, by a mile. For planned or ongoing borrowing, an overdraft is one of the most expensive ways to borrow in the UK — and this scenario shows why.
Scenario 3: The Regular £500 Dipper
Then there’s the most common pattern of all: not one big emergency, but a life lived £500 inside the overdraft, month after month.
Overdraft: an average £500 overdrawn at 39.9% EAR costs roughly £200 a year in interest. Every year. For nothing you can point to.
Low-rate credit card: a card with a 9.9% representative APR (several UK cards offer this to good-credit customers) used for the same £500 of rolling borrowing costs around £50 a year — a quarter of the price.
But the real fix for the regular dipper isn’t a different product — it’s a buffer. Build even £500 of your own money sitting in the account, set up low-balance alerts in your banking app, and review whether the recurring shortfall points to a budgeting gap. The cheapest borrowing is the borrowing you don’t need.
What Each Does to Your Credit Score
Cost isn’t the whole story. Here’s how lenders see each one:
- Arranged overdraft, used responsibly: staying within your agreed limit and paying it down regularly can actually help your score — it shows controlled borrowing. Unused overdraft limit even improves your credit utilisation ratio.
- Unarranged overdraft: going beyond your limit is a red flag. It lands on your credit report and signals to lenders that you’re struggling. This is the one to never, ever do.
- Credit card, paid in full: the gold standard. On-time payments, low utilisation, no interest paid. Lenders love this.
- Credit card, minimum payments only: worse than it looks. High utilisation plus slow repayment tells lenders you’re stretched — and the interest compounds monthly.
One more consideration: overdraft facilities can be reduced or withdrawn by your bank with little warning. A credit limit is more stable. If your entire financial buffer is an overdraft your bank could shrink next month, that’s a fragile plan.
FAQs
Overdraft vs credit card UK: which is cheaper for borrowing £1,000?
A credit card is cheaper for borrowing £1,000 in almost every case. A £1,000 arranged overdraft at 39.9% EAR costs roughly £33 a month in interest from day one, while a standard credit card at 24.9% APR costs less — and a 0% purchase credit card costs nothing at all if you clear it within the interest-free period. Overdrafts only compete for borrowing measured in days.
Is it bad to be in your overdraft every month?
Living permanently in your overdraft is expensive — around £200 a year in interest on a typical £500 balance at 39.9% EAR — and lenders may view persistent overdraft use as a sign of financial strain. If you’re in it every month, treat it as a symptom: build a small buffer, set low-balance alerts, and consider whether a 0% purchase card or a planned budget fix would break the cycle.
Can a credit card replace my overdraft?
Yes, and for most people it should. A money-transfer credit card can move cash into your current account at 0% for 12–24 months (for a 1–4% fee), directly replacing expensive overdraft borrowing. For day-to-day spending, a standard credit card paid in full each month gives up to 56 days of free borrowing — something no overdraft offers.
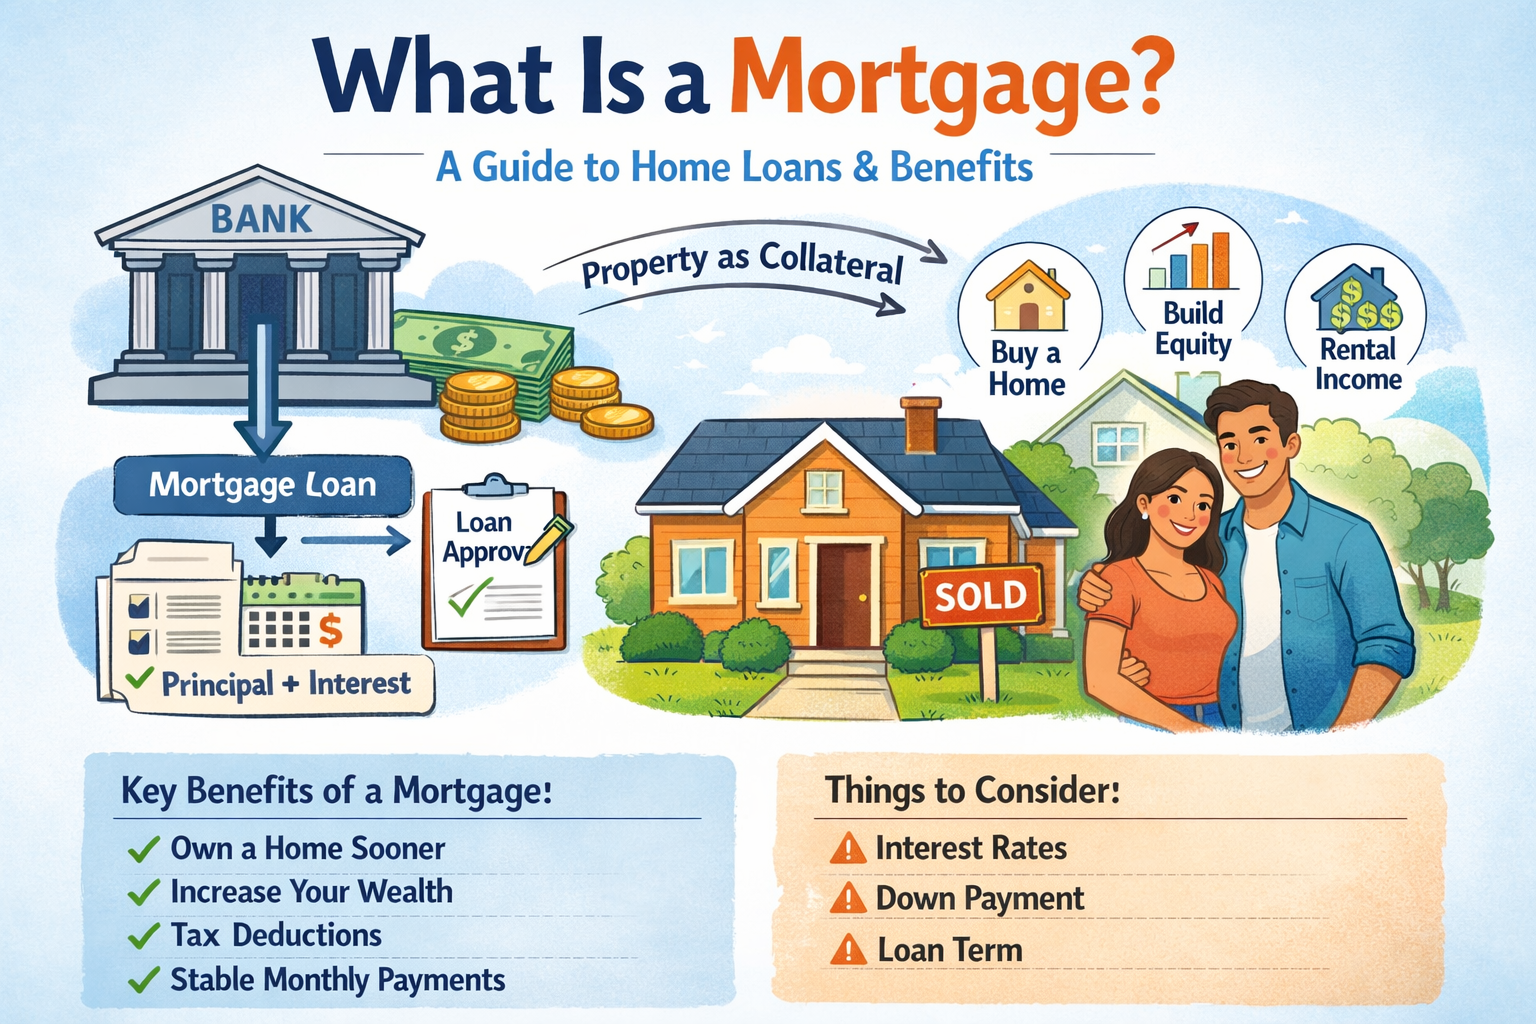
Does using an overdraft affect getting a mortgage?
An arranged overdraft used lightly won’t block a mortgage — lenders mainly check affordability and conduct. But heavy, persistent overdraft use can raise questions about your budgeting, and an unarranged overdraft on your credit file is a genuine black mark. If a mortgage application is on your horizon, clear the overdraft and keep the account in credit for several months beforehand.
The Bottom Line
Match the product to the shape of the gap. A few days’ timing mismatch? The overdraft’s convenience is fine — it’ll cost you about a pound. Anything measured in weeks or months? The credit card wins, and a 0% deal wins by a landslide. And if you’re living in your overdraft permanently, the product isn’t the problem — the budget is. Fix that, and the 39.9% meter stops running.
A credit card is cheaper for borrowing £1,000 in almost every case. A £1,000 arranged overdraft at 39.9% EAR costs roughly £33 a month in interest from day one, while a standard credit card at 24.9% APR costs less — and a 0% purchase credit card costs nothing at all if you clear it within the interest-free period. Overdrafts only compete for borrowing measured in days.
Living permanently in your overdraft is expensive — around £200 a year in interest on a typical £500 balance at 39.9% EAR — and lenders may view persistent overdraft use as a sign of financial strain. If you’re in it every month, treat it as a symptom: build a small buffer, set low-balance alerts, and consider whether a 0% purchase card or a planned budget fix would break the cycle.
Yes, and for most people it should. A money-transfer credit card can move cash into your current account at 0% for 12–24 months (for a 1–4% fee), directly replacing expensive overdraft borrowing. For day-to-day spending, a standard credit card paid in full each month gives up to 56 days of free borrowing — something no overdraft offers.
An arranged overdraft used lightly won’t block a mortgage — lenders mainly check affordability and conduct. But heavy, persistent overdraft use can raise questions about your budgeting, and an unarranged overdraft on your credit file is a genuine black mark. If a mortgage application is on your horizon, clear the overdraft and keep the account in credit for several months beforehand.