Before you sign any microloan agreement, you should know about the client protection principles microfinance lenders are supposed to follow. Drawn up by the industry’s Smart Campaign and now stewarded by SPTF, these seven rules are the closest thing microfinance has to a borrowers’ bill of rights. They cover everything from honest pricing to how you’re treated when you can’t pay. Most borrowers have never heard of them — which is exactly why lenders sometimes get away with ignoring them. Here’s what each principle means in plain language, and how to use them to protect yourself.
What Are the Client Protection Principles Microfinance Lenders Follow?
Think of the seven principles as the responsible industry’s promise to itself: serving poor clients profitably must never mean exploiting them. They spell out how products should be designed, prices disclosed, borrowers treated, and complaints handled. Certification programmes audit lenders against them, and growing numbers of investors require them. The catch? They’re voluntary in most markets. So real enforcement often comes down to you — the borrower who knows what to demand. Let’s walk through all seven.
The 7 Principles, Explained in Plain Language
1. Appropriate product design and delivery
Loans should fit your real life — repayments matched to your cash flow, not the lender’s targets. Done right: a market trader repays weekly on market days. Done wrong: a seasonal farmer is forced onto weekly repayments and defaults within two months. Before signing, ask: does this schedule match when I actually earn money?
2. Prevention of over-indebtedness
Lenders must check you can afford the loan — assessing your existing debts and income, and saying no when another loan would sink you. Done wrong: three different lenders each grant you a “small” loan in the same month. Total your repayments across all lenders before accepting anything new, and distrust lenders who never ask about your other debts.
3. Transparency
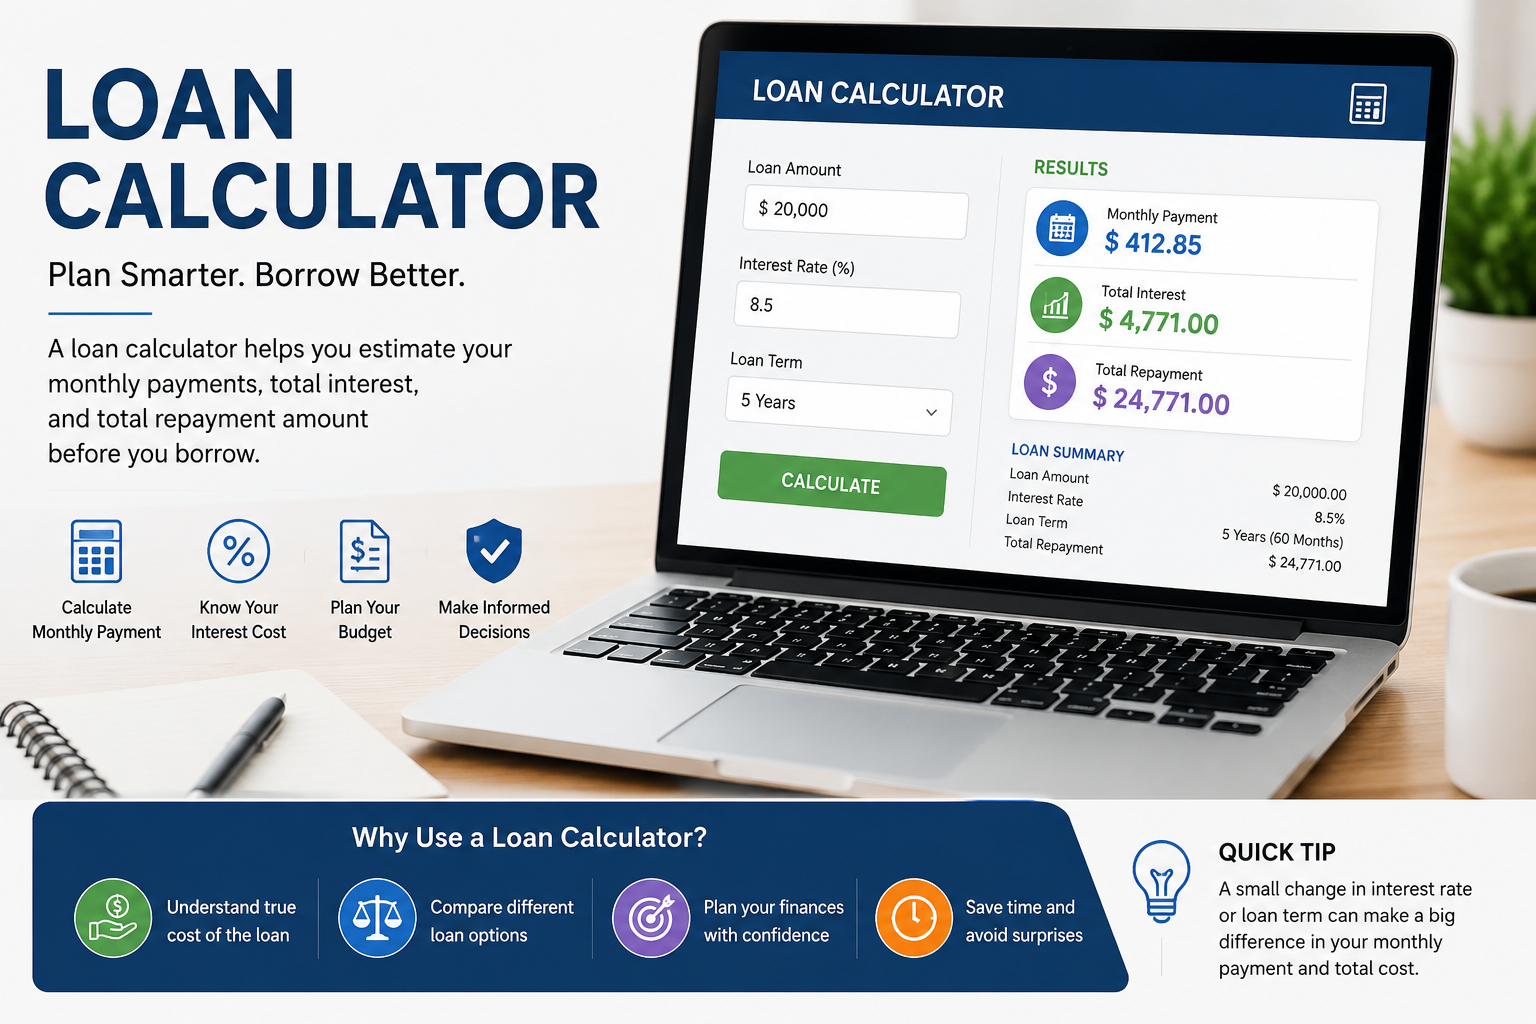
Every cost, fee, and condition must be disclosed clearly before you sign — in language you actually understand. Done right: the officer walks you through the total repayment amount, not just the monthly figure. Done wrong: “zero fee” banners hiding compulsory insurance deductions. Always ask: what is the total amount I will repay, in cash, over the whole loan?
4. Responsible pricing
Prices should be fair — covering the lender’s costs plus a reasonable margin, not squeezing maximum profit from captive borrowers. You can’t audit a lender’s books, but you can compare: get quotes from two or three lenders and ask each to justify the difference. Wildly higher prices with no better service are a red flag.
5. Fair and respectful treatment of clients
No abusive collection, no public shaming, no seizing household goods through intimidation. When recovery agents harass borrowers, this is the rule being broken. A decent lender trains staff in respectful collection and disciplines those who cross the line. Ask upfront: what happens if I miss a payment? The answer tells you everything.
6. Privacy of client data
Your personal and financial information belongs to you. Lenders must protect it and can’t sell or share it without your consent. With digital lending apps harvesting phone contacts and photos, this principle matters more than ever. Check what permissions a lending app requests — a loan app has no business reading your text messages.
7. Mechanisms for complaint resolution
When something goes wrong, you need somewhere to complain — and get an answer. Responsible lenders publish a complaints channel, acknowledge complaints promptly, and resolve them fairly. Before borrowing, ask: if I have a problem with this loan, who exactly do I call? If nobody can answer, walk away.
Why These Rules Matter More in 2026
The principles aren’t academic theory this year — they’re front-page news. On 9 October 2026, India’s Chief Economic Adviser warned the microfinance industry about over-lending and mis-selling to households that can’t absorb it, urging a shift toward savings and insurance. Every one of his complaints maps onto the client protection principles microfinance itself adopted years ago: mis-selling violates appropriate product design, over-lending violates the prevention of over-indebtedness, and hidden costs violate transparency. The lesson for borrowers is blunt: the industry’s own leadership admits the rules aren’t being followed everywhere. Knowing them is your first line of defence.
Your Pre-Signing Checklist
Turn the principles into five questions you ask every lender, every time. One: what is the total amount I will repay, including all fees? Two: does the repayment schedule match my income pattern? Three: what happens if I miss a payment — exactly? Four: who do I complain to if something goes wrong? Five: can I see all of this in writing before I sign? A lender answering all five clearly is probably safe. One who dodges, rushes you, or says “don’t worry, everyone signs this” is telling you all you need to know. Take the paperwork home if you can. The loan will still be there tomorrow — and so will you, better informed.
Frequently Asked Questions
Are these principles legally binding?
Mostly not — they’re voluntary standards, though some regulators have written similar rules into law. Their power comes from certification, investor pressure, and informed borrowers.
What should I do if a lender violates these principles?
Document everything: keep agreements, receipts, and messages. Complain through the lender’s channel first, then escalate to the financial regulator or microfinance association in your country. In many markets, regulators now take collection-abuse complaints seriously.
Do digital lending apps follow these rules?
Often worse than traditional MFIs, frankly. App lenders sometimes skip affordability checks entirely and harvest excessive phone data. The same seven principles apply — especially transparency, privacy, and fair treatment. If an app demands access to your contacts, treat it as a red flag.
Can I get out of a loan I shouldn’t have been given?
Sometimes. If a lender clearly skipped affordability checks or hid costs, regulators or ombudsmen in some countries can order restructured terms. Get advice from a consumer-protection organisation before stopping payments — defaulting without a plan usually makes things worse.
Conclusion
The client protection principles microfinance adopted were a genuine step forward — the industry admitting, in writing, that how it treats borrowers matters as much as how many it reaches. But principles on paper protect no one by themselves. They work when borrowers know them, ask the awkward questions, and walk away from lenders who can’t answer. Keep the five-question checklist with your loan papers: a lender who respects these seven rules is worth borrowing from. One who doesn’t was never on your side.