
What Is Mortgage and How Can You Benefit From It?
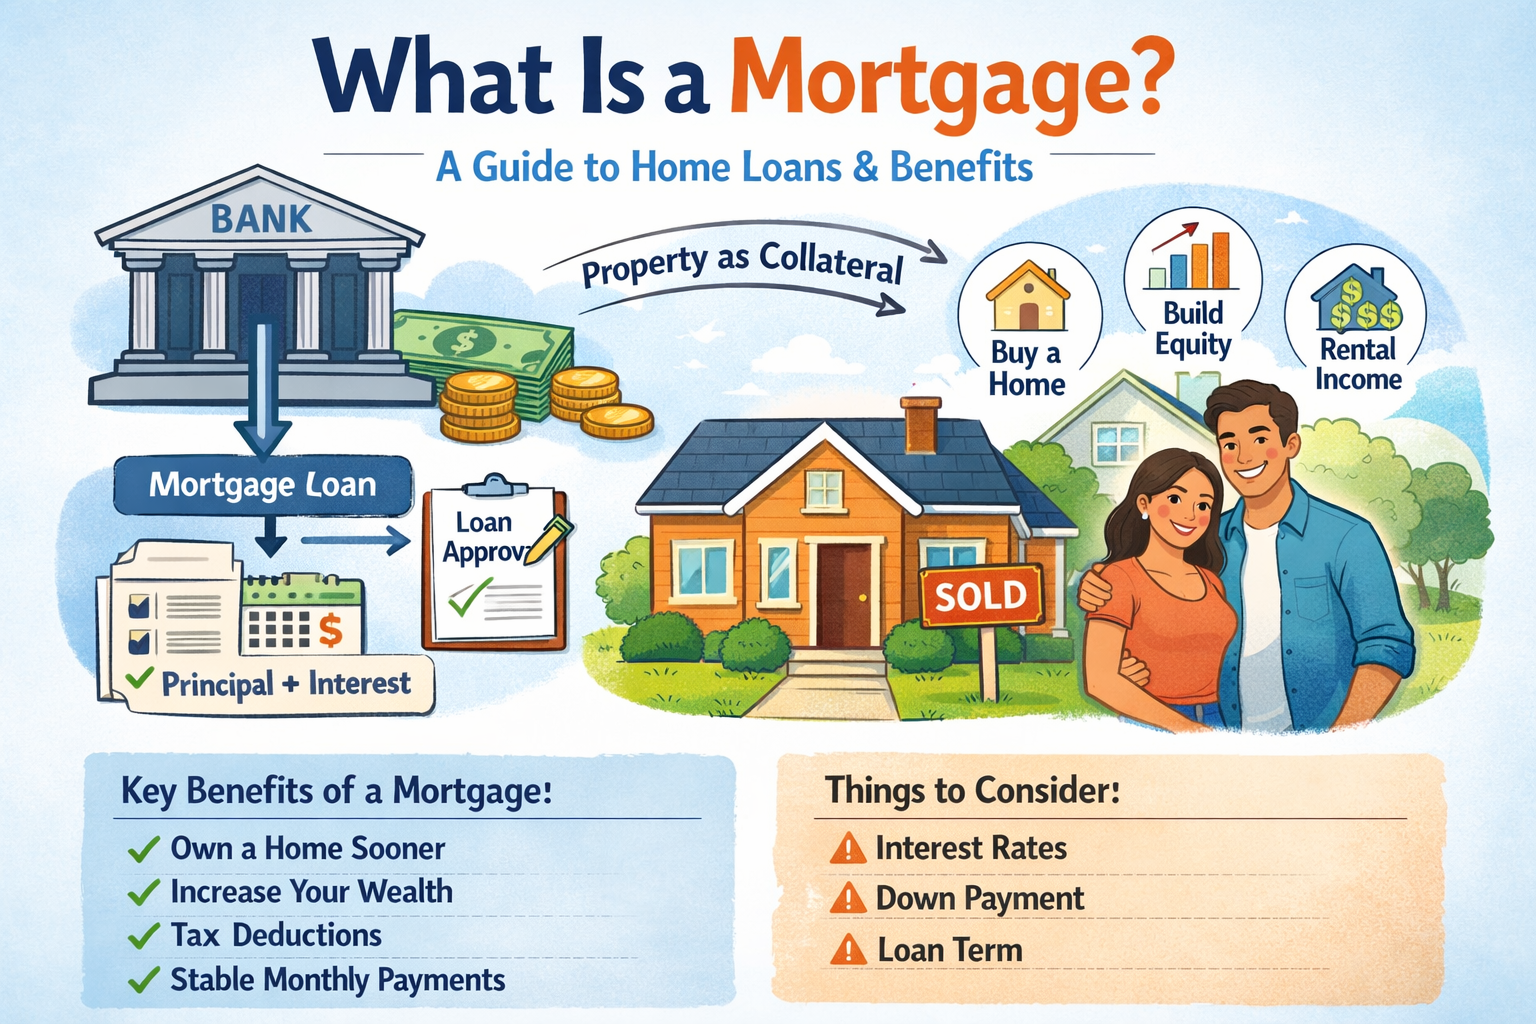
A mortgage is a type of loan that people use to buy property such as a house, apartment, or land. Instead of paying the full price of the property at once, a bank or financial institution lends money to the buyer. The buyer then repays the loan in small monthly payments over a long period of time, usually 10 to 30 years.
The important thing about a mortgage is that the property itself becomes the security for the loan. This means if the borrower fails to repay the loan, the bank has the legal right to take the property and sell it to recover the money. Because the property acts as security, banks are more willing to give large loans through mortgages.
Mortgage loans are widely used around the world and are offered by many financial institutions such as Wells Fargo, HSBC, and Bank of America.
How a Mortgage Works
The mortgage process is quite simple. First, a person chooses a property they want to buy. Then they apply for a mortgage from a bank or lender. The bank checks the person’s income, credit history, and ability to repay the loan. If the bank approves the loan, it pays most of the property price to the seller.
The borrower usually pays a down payment, which is a small percentage of the property price, often between 10% and 30%. The remaining amount becomes the mortgage loan.
After that, the borrower pays the bank every month. Each monthly payment usually includes two parts:
- Principal – the amount borrowed from the bank
- Interest – the cost of borrowing the money
Over time, these payments gradually reduce the loan amount until it is fully paid.
Types of Mortgages
There are several types of mortgage loans. The most common ones include:
1. Fixed-Rate Mortgage
In this type, the interest rate remains the same throughout the loan period. This means your monthly payment stays stable and predictable.
2. Adjustable-Rate Mortgage
Here, the interest rate may change after a certain period. Payments may increase or decrease depending on market interest rates.
3. Interest-Only Mortgage
For a specific period, the borrower pays only the interest, not the principal. After that period ends, full payments begin.
4. Reverse Mortgage
This type is designed for older homeowners who want to convert their home value into cash without selling their property.
Benefits of a Mortgage
Mortgage loans offer many advantages, especially for people who want to buy property but do not have enough money upfront.
1. Helps You Buy a Home Earlier
Without a mortgage, many people would need decades to save enough money to buy a house. A mortgage allows you to own a home immediately and pay for it slowly over time.
2. Builds Long-Term Wealth
Property values usually increase over time. When you buy a house with a mortgage, you are investing in an asset that may grow in value. After paying the loan, the property becomes fully yours.
3. Provides Financial Stability
Owning a home through a mortgage can provide stability for families. Instead of paying rent every month, you are investing in your own property.
4. Tax Benefits
In many countries, mortgage interest payments may be tax deductible. This can reduce the total tax amount a borrower must pay each year.
5. Opportunity for Rental Income
If you purchase a property using a mortgage, you may rent it out to tenants. The rental income can help cover the mortgage payments.
6. Improves Credit Score
Paying mortgage installments on time shows lenders that you are responsible with money. This can improve your credit score and make it easier to get future loans.
How Microfinance and Mortgages Can Work Together
In some developing countries, microfinance institutions help low-income families access housing loans. Organizations such as Grameen Bank have introduced housing finance programs that help people build or improve their homes through small, manageable loans.
These programs combine the principles of microfinance with housing loans, allowing families with limited income to gradually build safe and permanent homes.
Things to Consider Before Taking a Mortgage
Although mortgages are helpful, borrowers should carefully consider several factors before applying.
Interest Rates
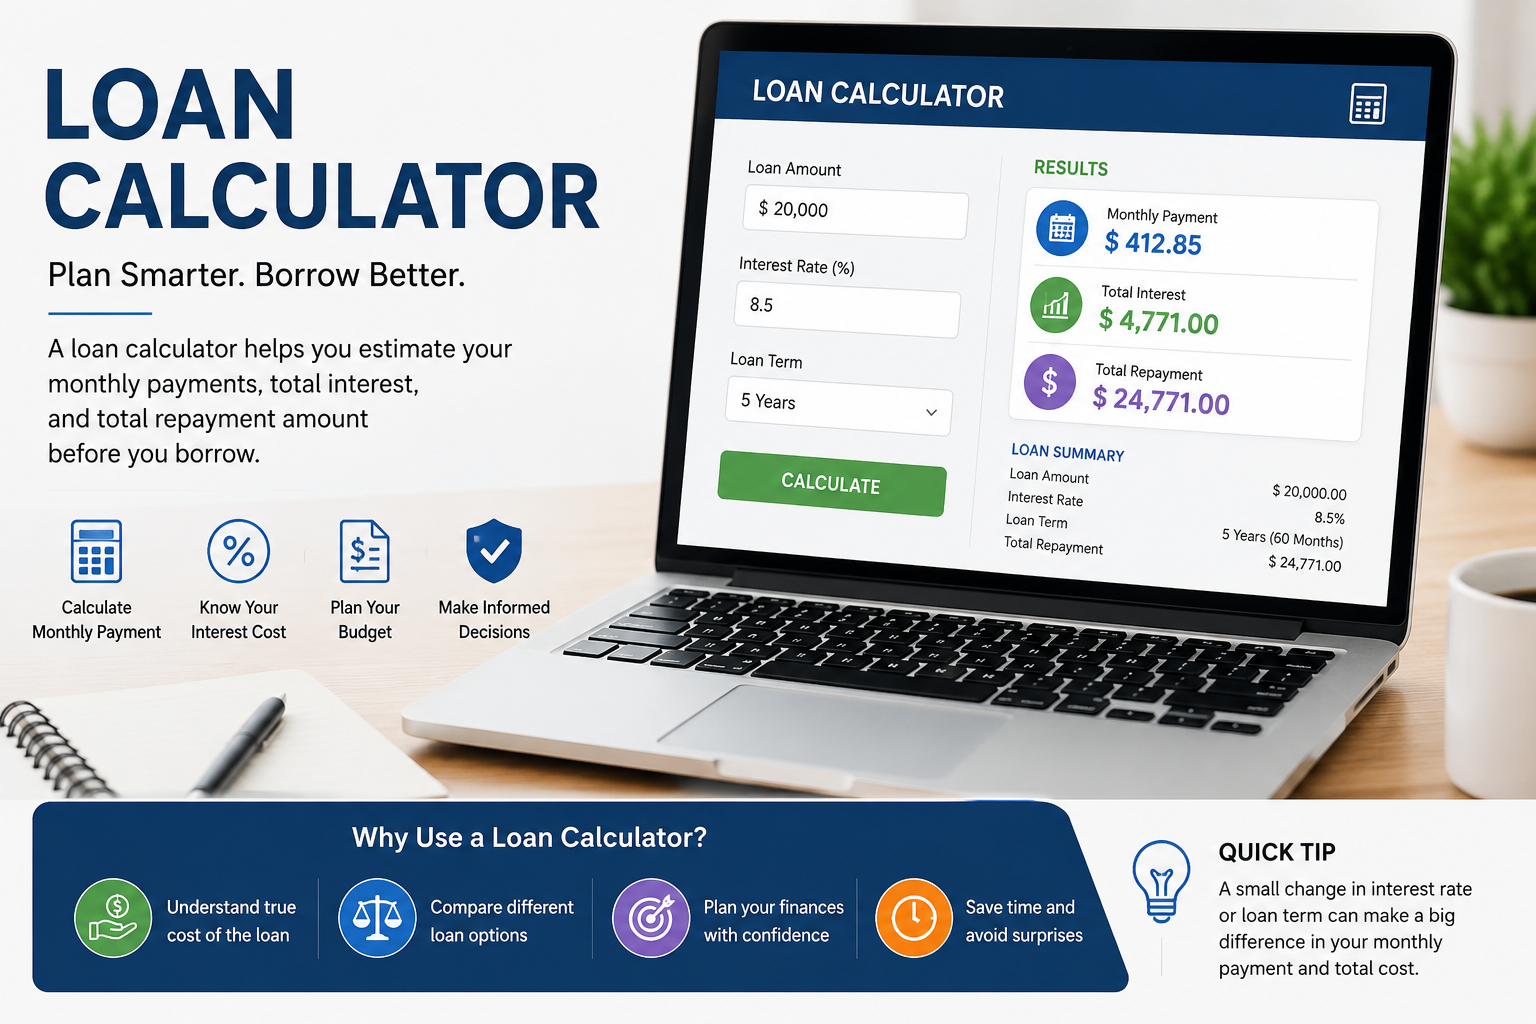
Different lenders offer different interest rates. A lower interest rate means smaller monthly payments and lower overall cost.
Loan Duration
A longer loan period means smaller monthly payments but more total interest paid over time.
Down Payment
A larger down payment reduces the total loan amount and monthly payments.
Financial Stability
Borrowers should ensure they have a stable income to pay the mortgage regularly. Missing payments can lead to penalties or even loss of property.
Risks of Mortgage Loans
While mortgages offer many benefits, they also come with some risks.
If a borrower cannot make the monthly payments, the lender can start a legal process called foreclosure, where the property is taken and sold to recover the loan amount. Also, rising interest rates in adjustable mortgages can increase monthly payments.
Therefore, it is important to borrow only what you can afford to repay comfortably.
Attanation
A mortgage is one of the most powerful financial tools that helps people purchase property without paying the full price upfront. By borrowing money from a bank and repaying it gradually, individuals and families can own homes, build long-term wealth, and achieve financial stability.
However, mortgages require careful planning and responsible financial management. Borrowers should understand the loan terms, interest rates, and repayment responsibilities before signing a mortgage agreement. When used wisely, a mortgage can be a valuable step toward property ownership and financial security.
credit score improvement tips, debt snowball calculator, debt avalanche calculator, financial wellness program, employee loan program, payroll advance program, microfinance app development, white label lending platform, loan management API, core banking system for MFI, mobile app for loan tracking
A mortgage is a loan used to purchase a home or property, where the property itself serves as collateral. Borrowers repay the loan with interest over a set term, typically 15 to 30 years.
You borrow money from a lender to buy a home, then make monthly payments covering principal and interest. If you fail to repay, the lender can foreclose and sell the property to recover the debt.
A mortgage lets you buy a home without paying the full price upfront, build equity over time, and potentially benefit from property appreciation. Mortgage interest may also be tax-deductible in some countries.
6 thoughts on “What Is a Mortgage? Home Loans, Benefits, and How Mortgages Work”