
Most people can tell you their salary down to the dollar, but ask them what they’re actually worth financially — assets minus debts — and most draw a blank. A net worth calculator answers that question directly. It’s not about how much you earn or how much you have sitting in a checking account; it’s a full picture of everything you own minus everything you owe, boiled down into a single number that tells you far more about your financial health than your income ever could. This guide walks through how to calculate your net worth properly, what to include and what to leave out, and how to actually use the number once you have it.
What a Net Worth Calculator Actually Measures
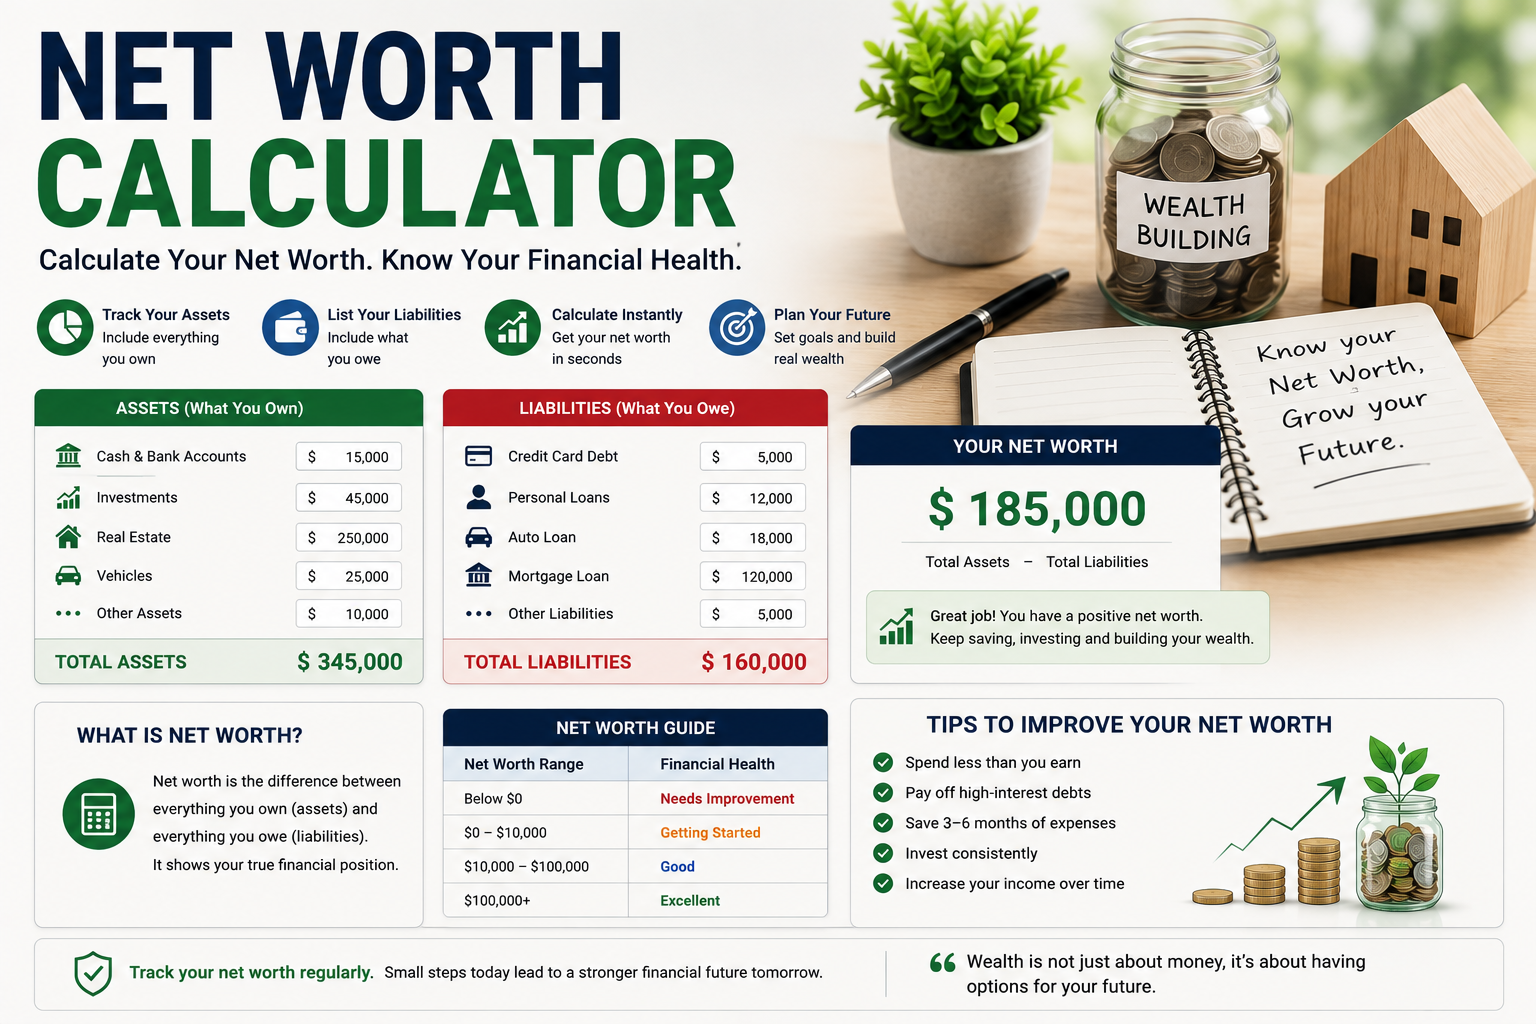
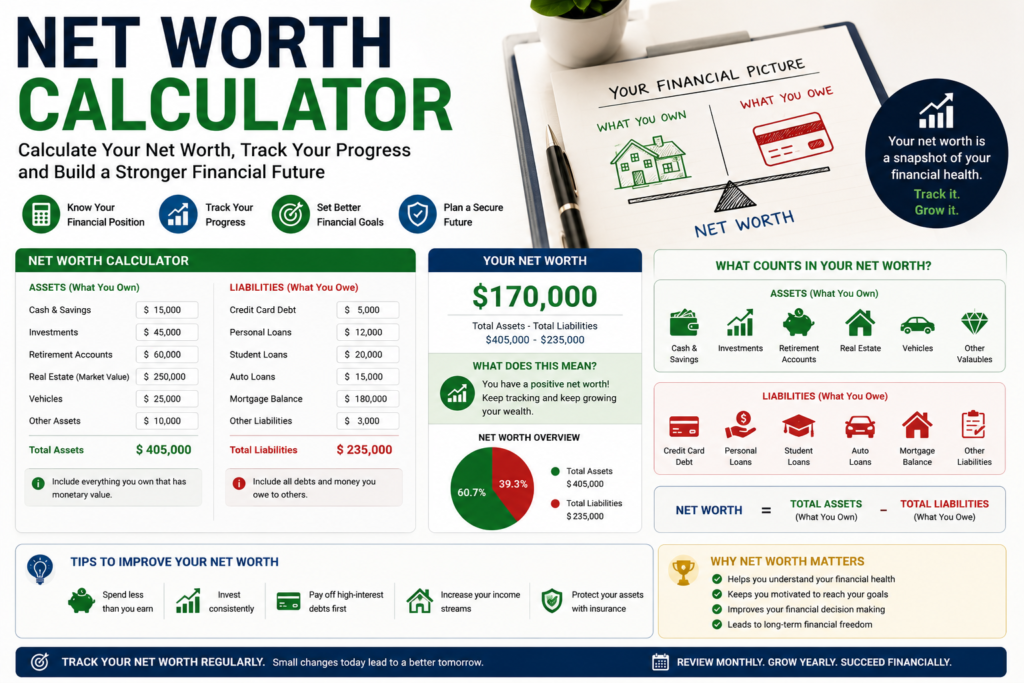
A net worth calculator adds up all your assets — the things you own that have monetary value — and subtracts all your liabilities — the debts you owe. What’s left is your net worth. A well-built calculator breaks this down clearly so you can see:
- Your total assets, categorized by type (cash, investments, property, and so on)
- Your total liabilities, also categorized (mortgage, credit cards, loans)
- Your net worth as a single bottom-line figure
- How that figure changes over time if you track it periodically
That last point is arguably the most useful part. A single net worth snapshot tells you where you stand today. Tracking it every few months or once a year tells you whether your financial decisions are actually moving you in the right direction — which is a far more meaningful signal than watching your income or your account balances in isolation.
What Counts as an Asset
Before you calculate anything, it helps to know exactly what belongs on the asset side of the ledger.
1. Cash and Cash Equivalents Checking accounts, savings accounts, and any cash on hand. This is the most liquid part of your net worth — money you could access immediately if needed.
2. Investments Retirement accounts, brokerage accounts, stocks, bonds, and any other investment holdings. Use current market value, not what you originally paid, since this reflects your actual position today.
3. Real Estate Your home and any other property you own, valued at current estimated market value rather than the original purchase price. This is one of the most commonly miscalculated categories, since people either use outdated purchase prices or overly optimistic estimates.
4. Vehicles and Other Valuable Property Cars, in particular, depreciate quickly, so use a realistic current resale value rather than what you paid. Other valuable personal property can be included, but it’s worth being conservative here rather than inflating your number with sentimental value.
What Counts as a Liability
Liabilities are just as important to get right, since underestimating debt inflates your net worth artificially.
- Mortgage balance — your remaining loan balance, not the original loan amount
- Credit card balances — current outstanding balances across all cards
- Auto loans — remaining balance owed, not the vehicle’s value
- Student loans and personal loans — total remaining balance across all loans
- Any other outstanding debt — medical debt, personal loans from family, or other obligations
A calculator that only tracks a mortgage while ignoring smaller debts like credit cards will overstate your actual position. Include everything, even debts that feel minor.
Net Worth Calculator
Apne assets aur liabilities enter karein — aapki net worth instantly calculate ho jayegi.
Assets (Asaasay)
Liabilities (Qarz / Den)
How to Read Your Results the Right Way
Once you’ve entered your assets and liabilities, don’t just look at the final number in isolation. Pay attention to:
- The composition of your assets — Someone whose net worth is almost entirely home equity is in a very different position than someone with the same total net worth spread across cash, investments, and property. A calculator that breaks down the composition, not just the total, gives you a much more useful picture.
- The ratio of liquid to illiquid assets — If most of your net worth is tied up in property or retirement accounts you can’t easily access, your day-to-day financial flexibility may be lower than your net worth number suggests.
- The trend over time, not the single snapshot — A single calculation is a data point. Recalculating every six or twelve months and comparing the trend tells you whether your saving, investing, and debt paydown habits are actually working.
Common Mistakes People Make With Net Worth Calculators
Using purchase price instead of current value for assets. This is especially common with real estate and investments. Always use realistic current market value, not what you originally paid.
Forgetting smaller debts. People often remember their mortgage and car loan but forget smaller credit card balances or personal loans, which can meaningfully skew the final number.
Including illiquid or sentimental items at inflated value. Personal belongings, collectibles, and similar items are easy to overvalue. If you include them at all, use a conservative, realistic resale estimate.
Calculating once and never again. A single net worth calculation is a snapshot, not a trend. The real value comes from recalculating periodically and watching the direction it moves, not from any one number in isolation.
Comparing your number to someone else’s. Net worth is highly dependent on age, income history, region, and life circumstances. The only comparison that’s actually useful is your own number against your own number from six or twelve months earlier.
A Simple Step-by-Step Way to Use One
- List all your cash and cash equivalents at current balances.
- Add up your investment accounts at current market value.
- Estimate your real estate and vehicle values realistically, not optimistically.
- List every liability — mortgage, credit cards, auto loans, and any other debt — at current outstanding balance.
- Subtract total liabilities from total assets to get your net worth.
- Note the composition of your assets, not just the total figure.
- Set a reminder to recalculate every six to twelve months and track the trend over time.
Final Thoughts
A net worth calculator gives you something your paycheck never will: an honest, complete picture of your actual financial position. It’s not about feeling good or bad about a single number — it’s about understanding what that number is made of, and tracking whether it’s moving in the direction you want over time. Calculate it honestly, using real current values rather than optimistic estimates, and revisit it periodically rather than once and forgetting about it. The trend, far more than any single snapshot, is where the real insight lives.
Net worth is what you own minus what you owe. Add up all assets (cash, investments, property) and subtract all debts (loans, credit cards, mortgages). The result is your net worth.
It gives you an honest snapshot of your financial health. Tracking it over time shows whether you’re building wealth or falling behind, and helps you set realistic money goals.
Recalculating every six to twelve months and comparing the trend is more useful than a single snapshot. Regular checks show whether your financial decisions are moving you in the right direction.
One thought on “Net Worth Calculator: How to Get an Honest Snapshot of Where You Actually Stand Financially”