If you’re asking how much you should save in your emergency fund, you’re already ahead of most people. Nearly half of adults in the US and UK say they couldn’t cover a surprise $500 or £500 bill without borrowing. A broken boiler, an emergency dentist visit, a sudden layoff — these things don’t ask if you’re ready. They just show up.
An emergency fund is cash set aside for genuine surprises, separate from everyday spending. Below is the full 2026 answer — the 3–6 month rule, a starter goal you can hit fast, a by-situation table, and exactly where to park the money.
How Much Should You Save? The 3–6 Month Rule
The standard advice from financial planners is simple: save 3 to 6 months of your essential expenses. It’s lasted for decades because it covers the most common emergencies — a job hunt, a car repair, a medical bill — without derailing your life.
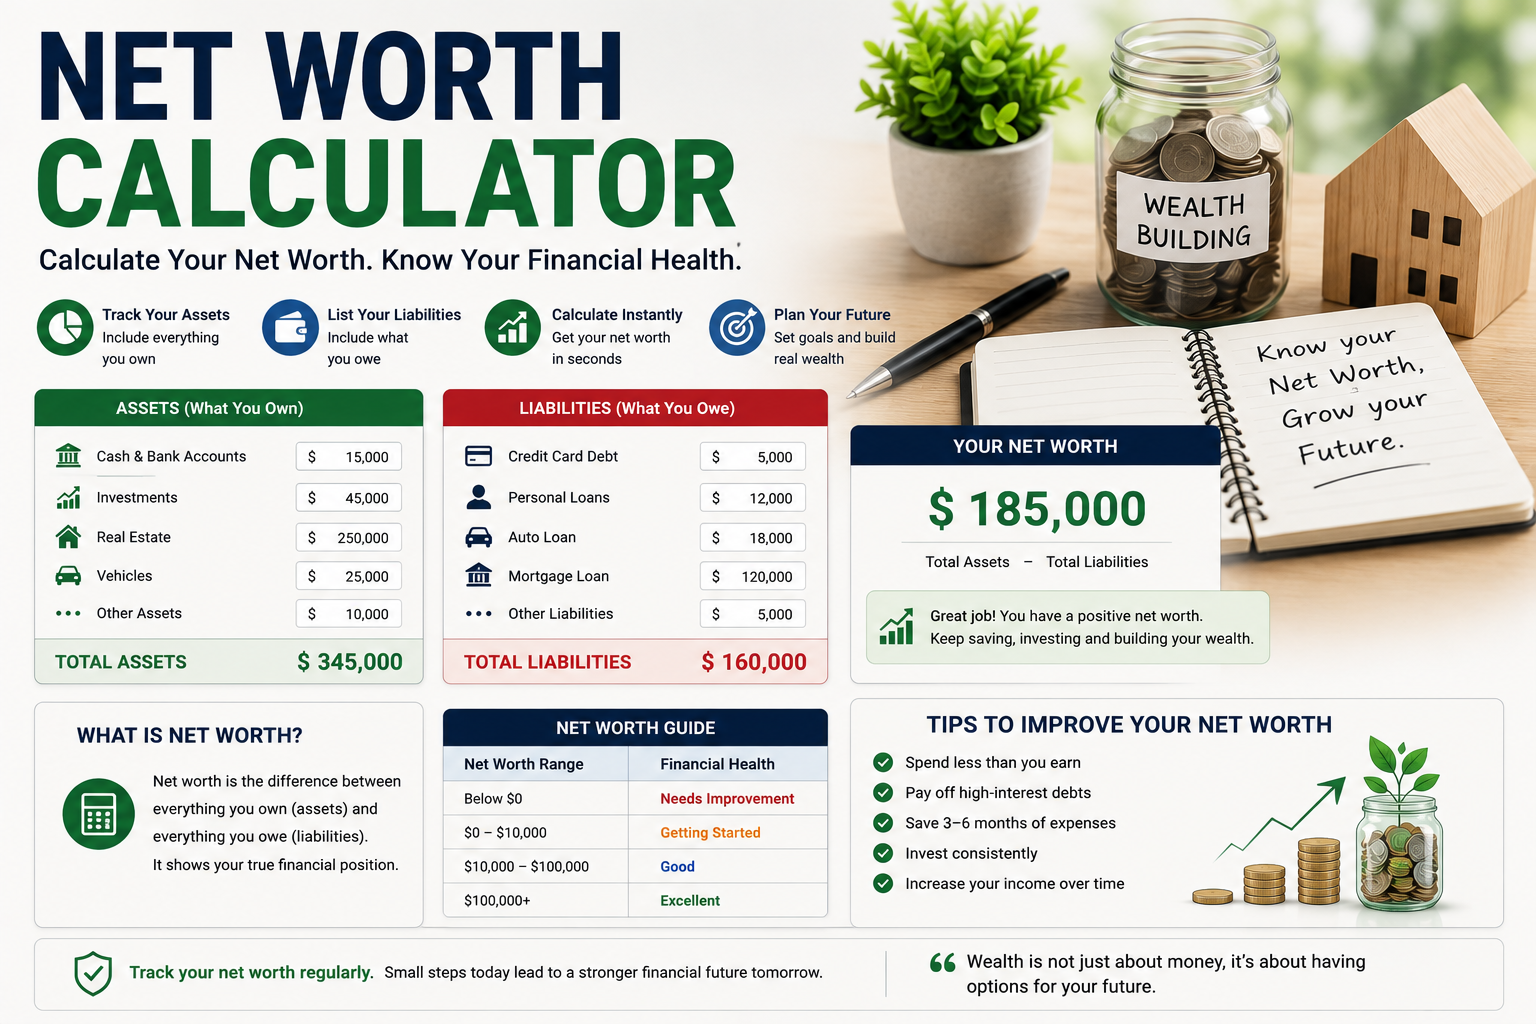
Here’s what most people get wrong: the number is based on your expenses, not your income. Your fund exists to keep your life running — rent paid, lights on, food in the fridge — while you deal with the crisis. Earn $6,000 a month but spend $3,800 on essentials? You don’t need $36,000. You need 3–6 months of $3,800: roughly $11,400 to $22,800.
To find your number, look at your last two or three bank statements and add up the non-negotiables: rent or mortgage, utilities, groceries, transport, insurance, minimum debt payments, childcare. Skip the dining out and subscriptions you could cancel. Multiply that monthly total by 3 for your minimum target and by 6 for the comfortable one. That range is your answer to emergency fund: how much should you save.
Emergency Fund: How Much Should You Save First? Start With $1,000 / £1,000
If the full target looks scary, start smaller. Most financial coaches recommend a starter emergency fund of $1,000 (or £1,000 in the UK) before anything else.
Why a thousand? Because most “mini-emergencies” — a dead car battery, a plumber visit, a cracked phone screen — land in the few-hundred range. Having that first thousand means a small surprise doesn’t become credit-card debt at 20%+ interest. Hitting one fast goal builds the saving habit far better than staring at a $20,000 target from zero.
The fastest way to get there:
- Open a separate savings account — not the one your debit card touches. Out of sight genuinely works.
- Automate a weekly transfer — even $40 or £30 a week tops $1,500 or £1,100 in about eight months, painlessly.
- Throw windfalls at it — tax refunds, bonuses, birthday money. Funnel at least half straight in.
- Sell stuff you don’t use — one clear-out can jump-start you by a few hundred dollars or pounds.
Once the starter fund is set, keep the same system running and build toward your full target. It doesn’t have to happen in a year. Slow and steady wins this one.
Emergency Fund: How Much Should You Save by Situation?
The 3–6 month rule is a starting point, not a one-size answer. Your job security and dependents change the math:
| Your situation | Recommended fund | Why |
|---|---|---|
| Stable job, two incomes | 3 months | Job loss is unlikely to hit both incomes at once |
| Stable job, single income | 3–4 months | One paycheck to protect, but steady work means faster recovery |
| Single-income household with kids | 6 months | No second income to fall back on |
| Freelancer or self-employed | 6–12 months | Irregular income, no employer safety net, dry spells happen |
| Commission or gig-based pay | 6 months | Earnings swing month to month, so the buffer must be thicker |
| Chronic health condition | 6+ months | Higher chance of surprise medical costs and missed work |
The pattern is simple: the less predictable your income, the bigger your fund. A tenured teacher and a freelance designer can both follow the rule — they just aim at different ends of it.
Quick Calculation: Find Your Number in 5 Minutes
Monthly essentials × your months of coverage = your target. Example: you live in Manchester and spend £1,900 a month on essentials (rent £1,100, bills £180, groceries £320, transport £140, insurance and minimum debts £160). Times 3 = £5,700 minimum; times 6 = £11,400 comfortable target.
Do the same with your numbers now. Essentials of $4,200 a month? Your range is $12,600–$25,200. Write it somewhere you’ll see it — a visible target is one you’ll actually chase.
Where to Keep Your Emergency Fund in 2026
Where the money sits matters nearly as much as how much you save. The rule: safe, insured, and accessible within a day or two. That rules out stocks and crypto — you don’t want your safety net dropping 20% the week you lose your job.
In 2026, a high-yield savings account is the sweet spot. As of late 2026, top online accounts pay around 4–4.5% APY versus under 0.5% at a typical traditional bank — on a $15,000 fund, that’s roughly $600+ a year in interest versus under $75. (Rates move with the economy, so check current offers when you open an account.)
In the US, choose accounts that are FDIC-insured (or NCUA-insured at credit unions) — deposits protected up to $250,000 per institution. In the UK, the equivalent is FSCS protection up to £85,000 per banking institution. Online banks typically pay the best rates. Avoid lock-ins like CDs with early-withdrawal penalties — emergency cash is for protection, not growth.
Emergency Fund FAQs
How much should I save if I have debt?
Build the $1,000 / £1,000 starter fund first, then attack high-interest debt aggressively. Once credit cards are cleared, grow the fund to your full 3–6 month target. Low-interest debt like a student loan can run alongside your saving.
Should my emergency fund be 3 or 6 months?
Stable job, no dependents? Three months is fine. Freelancer, single income, or health concerns? Aim for six or more. When in doubt, start at three and keep building.
Can I invest my emergency fund?
No — not in stocks, crypto, or anything that can drop quickly. The money must be there in full when you need it. Keep it in an FDIC-insured (or FSCS-protected) high-yield savings account earning around 4–4.5% APY in 2026.
What counts as a real emergency?
Job loss, urgent medical or dental bills, essential car or home repairs, emergency travel. A sale, a holiday, or a new phone doesn’t count. Unsure? Ask: “Will waiting make this cost a lot more?” If yes, it’s probably genuine.
Conclusion
So — emergency fund: how much should you save? Start with $1,000 or £1,000 as fast as you can, then build toward 3–6 months of essential expenses, adjusted for your situation. Keep it in an insured high-yield savings account where it earns a solid return while staying one click away.
The best emergency fund isn’t the biggest one — it’s the one that actually exists. Start this week, automate a transfer, and let it quietly do its job in the background. Future you will be glad you did.